• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

The Grandparent Spending Problem: What to Do When They Keep Buying Your Kids Everything

August 23, 2026 | Leave a Comment

Grandparent With Grandkids
Grandparents love showing affection through gifts, but excessive spending can leave parents managing clutter, conflicting expectations, and difficult family conversations. Clear boundaries can keep generosity focused on what children value most: meaningful relationships and time together. (Pexels).

Grandparents often show love through generosity, but there is a point when another toy, outfit, gadget, or surprise stops feeling helpful. For parents, too much grandparent spending can create clutter, undermine household rules, and teach children to expect a purchase every time Grandma or Grandpa visits. This is hardly a small phenomenon: AARP’s 2026 research found that 90% of grandparents provide financial support to grandchildren, spending an average of $2,654 annually across their grandkids. Collectively, grandparents provide an estimated $172 billion in direct financial assistance every year, on top of hundreds of billions of dollars’ worth of unpaid care. The goal is not to discourage that generosity but to make sure it strengthens the family instead of becoming a source of conflict.

First, Decide Whether You Actually Have a Spending Problem

A grandmother who occasionally arrives with a coloring book is different from a grandparent who buys expensive electronics after a parent has specifically said no. Before starting a potentially uncomfortable conversation, identify what is actually bothering you about the spending. Is your house overflowing with toys, are grandparents disregarding your rules, are siblings receiving noticeably different gifts, or is your child beginning to associate visits with getting something? The distinction matters because a little harmless grandparent spoiling may not require the same response as repeated purchases that interfere with parenting decisions. Establishing exactly which behavior needs to change makes it much easier to communicate a reasonable boundary.

Explain the Problem Without Criticizing Their Generosity

Starting with “You buy them too much stuff” can immediately put grandparents on the defensive, so focus instead on what is happening in your household. You might explain that toys are overflowing from the playroom, your child has started asking grandparents for purchases, or expensive gifts are conflicting with lessons you are teaching about money. ZERO TO THREE found that disagreements between parents and grandparents frequently stem from mismatched expectations and recommends discussing boundaries and caregiving approaches openly. Research from the C.S. Mott Children’s Hospital National Poll has similarly found that disagreements with grandparents are common, with 43% of parents reporting at least minor disagreements over parenting choices. A simple “We love how generous you are, but we need your help keeping gifts manageable” acknowledges the good intention while making clear that parents still set the household rules.

Create a Gift Rule Everyone Can Actually Understand

“Please don’t buy so much” is difficult to follow because Grandma’s definition of “too much” may be completely different from yours. Instead, establish a rule that removes the guesswork: one birthday gift and one experience, a $50 limit for ordinary visits, no gifts outside birthdays and holidays, or approval from a parent before any purchase over a certain amount. Parents could also create a shared wish list containing toys, books, clothing sizes, activities, and other things the children genuinely need or want. Using approximately the same rules with both sides of the family can help avoid arguments about one set of grandparents receiving more freedom than another. The objective is not controlling every dollar grandparents spend but giving their generosity some guardrails.

Separate “Spoiling” From Undermining a Parent’s Decision

This distinction deserves particular attention because not every unwanted gift is equally serious. If Grandpa slips your daughter an extra cookie, you may decide that is part of the fun of having grandparents; if he buys her a smartphone after you explicitly said she was not ready for one, that is a parenting-boundary issue rather than merely excessive spending. ZERO TO THREE recommends identifying which family rules are essentially “carved in stone” and which ones have room for flexibility when grandparents are involved. Parents can apply the same principle to money by deciding beforehand which purchases are harmless indulgences and which require permission. That gives grandparents some freedom to enjoy their role without allowing expensive gifts to override decisions that belong to Mom and Dad.

Give Grandparents Better Ways to Spend

Simply saying “stop buying things” removes an activity grandparents may genuinely enjoy, so give them alternatives. Suggest zoo trips, baking afternoons, movie outings, museum memberships, books, craft projects, camps, sports fees, or contributions toward activities the child already enjoys. The latest AARP research shows grandparents already provide financial assistance far beyond toys, including clothing, food, school supplies, childcare, camps, travel, and even medical expenses. Grandparents interested in larger financial gifts could also talk with parents about education savings or other long-term goals rather than surprising a child with another expensive gadget. Redirecting generosity lets grandparents continue experiencing the pleasure of giving while parents have more control over what enters the house.

Try the “Something, Somewhere, Someday” Rule

Families overwhelmed by gifts can divide grandparent generosity into three simple categories: something to have, somewhere to go, or something for someday. “Something” might be one birthday toy or outfit, “somewhere” could be tickets to the aquarium or a grandparent-grandchild outing, and “someday” could mean money toward education or another future goal. Grandparents still have several ways to give, but every visit no longer produces another bag of toys for the parents to store. Older children can even participate by choosing whether they would prefer an item, an experience, or money saved toward a larger goal. That turns grandparent generosity into an opportunity to teach children that money can buy more than immediate possessions.

What If Grandma Keeps Ignoring the Rule?

This is the missing section I’d definitely add because setting a boundary does not guarantee someone will follow it. If a grandparent repeatedly ignores an agreed gift limit, parents can calmly establish what happens to unapproved purchases before the next one appears. An excessive toy might stay at Grandma’s house, be returned, be saved for the child’s birthday, or require the child to choose an existing toy to donate before keeping it. The consequence should not be designed to punish the grandparent or embarrass the child; it should simply prevent ignoring the rule from making the rule meaningless. Research on parent-grandparent disagreements has found that unresolved differences can affect family relationships, making consistent communication preferable to allowing resentment to accumulate.

Protect the Grandparents’ Finances Too

Sometimes the biggest concern is not what children are receiving but whether grandparents can actually afford to keep giving it. AARP reported on a 2025 survey in which 17% of grandparents said they felt pressured to contribute more than they could afford, while 11% said they had withdrawn money from savings or retirement accounts to help their grandchildren. Parents who notice expensive gifts arriving despite a grandparent’s tight budget should consider saying explicitly that nobody expects them to compete with the other grandparents or finance experiences they cannot comfortably afford. Grandparents approaching or already living in retirement have their own housing, healthcare, emergency, and long-term-care expenses to consider. No gaming system, vacation, or birthday extravagance is worth compromising Grandma or Grandpa’s future financial security.

Make Memories the Thing Grandkids Expect

The long-term goal is not for grandchildren to think, “Grandma doesn’t buy me things anymore.” It is for them to think, “When Grandma comes over, we do something together.” Create traditions that have little connection to money: Saturday pancakes, planting a garden every spring, baking birthday cakes together, library trips, movie nights, fishing, crafts, or an annual sleepover. AARP’s 2026 study found that 79% of grandparents described the grandparent experience as extremely or very fulfilling, while grandparents who provide care average more than 500 hours annually with their grandchildren. Those numbers are a useful reminder that the grandparent-grandchild relationship is already enormously valuable before anyone walks into a store.

Generosity Works Better When Everyone Knows the Rules

Grandparents should be allowed to enjoy spoiling their grandchildren a little, and parents do not need to police every ice cream cone or surprise book. The problem begins when spending undermines parenting decisions, creates expectations in children, overwhelms the household, causes family resentment, or threatens a grandparent’s own finances. Clear rules, approved wish lists, experience gifts, future-oriented giving, and predictable consequences for major boundary violations can preserve generosity without allowing purchases to control the relationship. Most importantly, children can learn that Grandma and Grandpa’s value comes from the relationship they share, not from what appears in their shopping bags.

Have grandparents ever bought your children more than you were comfortable with, and how did you handle it without damaging the relationship?

What to Read Next

8 Things Grandparents Buy Kids That Parents Secretly Wish They Wouldn’t

6 Budgeting Hacks from Depression Era Grandmothers

8 Reasons Your Kids Prefer Staying with Grandma—And It’s Not Just the Snacks

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: family finances, family relationships, gift giving, grandchildren, grandparent spending, grandparents, money, Parenting, parenting boundaries, Raising Children

Life Insurance: A Must Have for New Parents

November 4, 2025 | 2 Comments

new parentsIf you’re planning to have a baby soon, you may be overwhelmed by the expenses you’re facing.  All that new baby gear costs quite a pretty penny!  There are so many must-haves:  a crib, changing table, bouncy seat, baby tub, just to name a few.  Marketers would like you to believe that this is just the beginning of the items you’ll need for the baby.

Don’t forget other necessities like diapers, wipes, formula.

Whew.  Are you getting nervous yet?

While you may resign yourself to paying for these items, one important item you may not even consider is life insurance.

If you don’t have life insurance yet, you’ll want to get a policy as soon as the baby is born.  Hopefully you’ll live a nice, long life, but if you don’t, you want to leave money so that your spouse or another caregiver can afford to raise your child.


Why Life Insurance Through Your Employer Shouldn’t Be Your Only Policy

You could get a fairly low cost policy through your employer, but this is a risky strategy.  Remember, if you leave this job, you’ll forfeit the company’s life insurance policy.  While that makes little difference if you’re healthy, if you develop a health condition before you leave your job, you’ll be hard pressed to find an insurer that will issue you a life insurance policy for a premium you can afford.

You could take out employer-based life insurance as a supplemental policy, but it shouldn’t be your only policy.


How to Reduce the Cost of Private Life Insurance

It’s far better to get your own private health insurance.

I know, you may think that is one more expense that you really can’t afford, but the simple truth is that you cannot NOT afford a life insurance policy.

The good news, though, is that if you’re healthy, you’ll likely find that a private life insurance policy is not as pricey as you think.  Our friend Jeff Rose has some great tips on how to get the best rates on life insurance.
There are other strategies, too.  If you’re overweight when you initially get your policy but you lose weight and get into a healthy weight range, your premium might be adjusted to cost you less (because the insurer’s risk is lower).  Usually, you need to maintain this weight loss for at least a year and also have a doctor’s notice that you’ve maintained the weight loss for that duration.

The same consideration might be given to a smoker who has become a non-smoker.

Finally, remember that shopping around for the lowest policy is an excellent way to reduce costs.  You’ll likely be surprised how much the same insurance policy’s premium can vary from company to company.

While you likely don’t want to think about life insurance, if you’re having a baby, you must protect yourself and your child with a good life insurance policy.

Do you have life insurance to protect your family?

Brian
Brian

Brian is the founder of Kids Ain’t Cheap and is now sharing his journey through parenthood.

 
Email • Google + • Facebook • Twitter

Filed Under: Money and Finances Tagged With: Insurance, life insurance, money, new parent

8 Irresponsible Purchases Parents Are Making For Their Children

April 25, 2025 | Leave a Comment

8 Irresponsible Purchases Parents Are Making For Their Children
Image Source: Pexels

As parents, we all want to give our children the best lives possible. If you didn’t have a lot growing up, you probably don’t want your kids to experience the disappointment of going without. However, it’s important not to go overboard and make irresponsible purchases for your children. Kids don’t need luxuries like designer goods or in-app purchases to thrive. In fact, overindulging your kids can spoil them and make them less grateful. Here are 8 irresponsible purchases you should consider skipping.

1. Designer Goods 

Designer Goods
Image Source: Pexels

If your child doesn’t wear a uniform to school, he or she may feel pressure to keep up with other kids and wear designer clothes. Your kids probably think they need to rock Air Jordan sneakers or expensive Lululemon gear to become popular. 

But buying your children pricey clothes is teaching them the wrong lesson—that they have to dress to impress to be accepted. It may be better to skip this irresponsible purchase and tell your kids that they have great personalities, regardless of what they’re wearing. 

2. In-App Purchases

In-App Purchases
Image Source: Pexels

Many games that are popular with kids, including Roblox and Fortnite, allow kids to make in-app purchases to upgrade their character. These digital points can be surprisingly pricey. According to Statista, 40% of families spend between $10 and $100 per month on in-app purchases. 

Although gaming can boost creative expression, it’s important to limit your child’s screen time and in-app purchases. Games can feel real to kids and become kind of addictive. If your child has trouble putting the controller down when asked or makes excessive in-app purchases, it’s probably time to cut back on screens. 

3. iPhones 

iPhones
Image Source: Pexels

iPhones tend to be very expensive, especially if you purchase a brand new one from Apple. For example, the iPhone 16 Pro model starts at about $999. Kids are often more likely to lose or mistreat their belongings than adults. 

If your child is getting their first phone, it may be better to start with a cheaper brand while they learn digital responsibility. Once they prove that they can handle their new device, you could discuss upgrading their phone as a Christmas or birthday gift. Or better yet, ask your child to contribute some of their savings to the purchase price of the phone. 

4. Junk Food 

Junk Food
Image Source: Pexels

Kids of all ages love sugary snacks and junk food. Your kids probably beg for treats like soda and cereal at the store. Although it’s tempting to give in, holding firm can help safeguard your children’s health. 

We all know that kids would eat a big bowl of ice cream for dinner if allowed. But they usually don’t understand the negative consequences of eating too much junk food, such as lack of energy, poor academic performance, and weight gain. Even if your kids don’t like vegetables, it’s important to keep serving them a balanced diet to set them up for success. 

5. Pets

Pets
Image Source: Pexels

Pets can teach children responsibility, but parents often end up doing all of the work. Kids who swear they’ll walk the dog before you adopt them often stop after a few weeks when the novelty starts to wear off. While there is no shortage of child-appropriate pets, from dogs and cats to fish, gerbils, and small reptiles, each come with their own unique needs. 

When looking at adding a pet to your family, make sure you think about which type of pet will fit with your family’s lifestyle the best. While fish aren’t snuggly or playful in the same way a dog is, they also need much less active care and attention, making them a better fit for families who are out of the house most of the day.

6. Beauty Products 

Beauty Products
Image Source: Pexels

Children have become enamored with beauty products after seeing them on social media. Kids as young as six have skincare routines, even though all they need is a gentle soap or lotion at most. 

Children have thinner, more sensitive skin than adults, so using these “anti-aging” or “brightening” products can cause facial irritation and breakouts. Allowing your kids to use makeup at a young age can also cause skin issues like rashes and redness. 

7. Too Many Toys 

Too Many Toys
Image Source: Pexels

If your kids ask for new toys constantly and you always say yes, you’ll amass a giant pile of action figures. Plus, when kids have too many toys, they may get overwhelmed and have a hard time playing with everything. Being mindful of the requests you say “yes” to can help you avoid this problem. 

Try to opt for items that offer high replayability value and are different from ones your child already has. Kids get lots of toys for birthdays and holidays, so refrain from buying them anything new as those dates approach. 

8. Huge, Expensive Birthday Parties

Huge, Expensive Birthday Parties
Image Source: Pexels

Do you remember watching My Super Sweet 16 growing up? The teens on the show had generous parents who threw them huge parties and gave them lavish gifts. However, many of the teens seemed dissatisfied and entitled. 

Although you want to celebrate your child on their birthday, spoiling them with over-the-top parties and presents may not be the right approach. Going overboard and splurging on balloon arches and pony rides could give your kids unrealistic expectations and make them less grateful overall. 

Is there anything you won’t buy for your kids for their own good? Share your thoughts in the comments.

Read More:

Should People Be Fined for Having Too Many Kids?

Do You Need Kids To Live a “Fulfilled” Life?

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: Gifts, money, Spending

9 Money Moves Every Teen Should Know Before They Turn 18

March 26, 2025 | Leave a Comment

9 Money Moves Every Teen Should Know Before They Turn 18
Image Source: Pexels

There are many financial concepts your teen will need to understand by the time they reach adulthood, such as saving, investing, and building credit. Some schools don’t offer courses on personal finance for teens, so parents may be solely responsible for teaching their kids about money. To help you craft a lesson plan for your child, here are 9 money moves every young adult should know about before they turn 18. 

Personal Finance for Teens: 9 Essential Money Moves 

1. Creating a Budget

Creating a Budget
Image Source: Pexels

The most important element of personal finance for teens is budgeting. Teens who have a part-time job often blow their earnings on eating out and shopping. Helping your teen create a budget can prevent them from wasting their hard-earned cash. Everyone prefers different budgeting methods, so teach your kids various money management styles. 

A good one to start with is the 50/30/20 rule, which involves setting aside 50% of your income for necessities, 30% for fun, and 20% for savings. Since teens usually don’t have bills to pay, they can up their savings percentage, enabling them to build a nest egg for their future. 

2. Tracking Spending 

Tracking Spending
Image Source: Pexels

It’s not enough to simply set up a budget with your child. They need to learn how to track their spending and make sure they’re actually following their financial plan. Budgeting apps can streamline personal finance for teens by helping them keep tabs on their purchases. Apps like EveryDollar and You Need a Budget make it easy for young adults to see where their money is going and course correct if needed. 

3. Building Good Credit 

Building Good Credit
Image Source: Pexels

Although teens can’t take out loans or open credit cards yet, they should still understand how credit scores work. Credit scores track how well each person handles and repays debt. Adults who pay their bills on time and don’t take on too much debt usually have good credit scores. Because lenders use credit scores to screen loan applicants, building good credit is crucial for teens who dream of buying a home or starting a business someday. 

Teens whose parents have good credit can ask mom and dad about becoming an authorized user on one of their credit cards. Minors can be added to a guardian’s credit account, allowing them to start establishing credit history early. Once they turn 18, young adults can consider applying for a secured credit card of their own to build a positive payment history. Secured credit cards are often easier to get approved for than regular unsecured cards because they require an upfront cash deposit, which serves as collateral. 

Teens should also understand that there are different types of bank accounts. High-yield savings accounts offer a higher APY, or average percentage yield. This figure represents how much interest an account holder will earn on their savings each year. On the other hand, checking accounts provide much less interest, but make it easy to pay bills and receive direct deposits from work. Don’t forget to explain bank account bonuses to your teen, which are often available to adults who open an account at a new bank. 

4. Setting Up a Bank Account 

Setting Up a Bank Account
Image Source: Pexels

Another important aspect of personal finance for teens is banking. Opening a bank account will give your teen a secure place to save funds from summer or part-time jobs, making it easier to reach their financial goals. Since minors usually can’t open a bank account on their own, you’ll have to help your child get set up. Banks typically require both the parent and the child to bring valid forms of identification, such as a birth certificate, passport, or driver’s license. You may also need to provide personal information like your address and Social Security number. 

5. Investing 

Investing
Image Source: Pexels

Ideally, personal finance for teens should also involve investing. Parents can open investment accounts on their child’s behalf, such as a 529 for educational savings or a custodial brokerage account. Although you’ll be managing the account until they reach the age of majority, you can still use the account to teach them about investing. Encourage them to check the balance with you and discuss which assets you’ve chosen and why. Covering important topics like compound interest and diversification will help prepare them to manage their own portfolio as adults. 

6. Setting Realistic Financial Goals 

Setting Realistic Financial Goals
Image Source: Pexels

Sometimes teens have unrealistic salary expectations and financial goals. According to Bank of America, teenagers think they’ll pay off their student debt, save $100K, and own a home all by age 30. Make sure to explain to your child that meeting lofty financial goals requires a high income. Discuss the average salary new grads earn, and cover lucrative jobs and career paths that would allow them to build wealth more quickly. 

If their career aspirations won’t make them rich, teach your kids how to set more attainable financial goals. Showing them your budget and bills will help them understand the cost of necessities. Add up their expected expenses and show them how much money they might have left over each month. This hands-on budgeting lesson will right-size their financial expectations. 

7. Job Search Skills 

Job Search Skills
Image Source: Pexels

Job search skills should also be part of any discussion about personal finance for teens. Even if your child is too busy to get a job now, they should understand how to find and apply to roles on sites like Indeed. With parental consent and assistance, teens may even be able to set up a LinkedIn account to learn about networking. Teaching your child interview skills is also crucial. Understanding how to frame their experience and skills to interviewers will help them get a solid foothold on the career ladder after graduation.

8. Understanding Debt

Understanding Debt
Image Source: Pexels

For teens, credit cards can seem like free money. That may be why young adults rack up an average credit card balance of $2,319 by age 20, according to Bank of America. It’s important to ensure your teenager understands how debt and APRs work. 

The annual percentage rate expresses the annual cost of borrowing money as a percentage. Show your teen the average APR for credit cards and calculate how much interest they’d pay on small and large balances. Seeing how interest costs stack up and make it hard to pay off credit card debt may help your young adult avoid costly financial mistakes. 

9. Planning for Education Costs

Planning for Education Costs
Image Source: Pexels

Once your teen understands how debt works, they may be eager to find alternative ways to fund their college education. Explain that student loans aren’t the only way to pay for trade school or university. Your child can apply for financial aid, merit scholarships and grants, or get a part-time job to start saving now. With proper time management skills, they can also work while they study to help cover living expenses and tuition. 

Although your child may have a dream school in mind, make sure to discuss the benefits of choosing a cheaper college. Attending community college first or picking an in-state school can help lower tuition costs, reducing their debt burden after graduation.

Are there any personal finance lessons you wish you had learned before you turned 18? Share your experience in the comments.

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: kids and finances, money, teens

5 Reasons Why Texas Daycare Costs Are Skyrocketing (and How to Cope)

March 12, 2025 | Leave a Comment

5 Reasons Why Texas Daycare Costs Are Skyrocketing (and How to Cope)
Image Source: Pexels

Child care has always been expensive, but the average cost of daycare in Texas has skyrocketed over the past few years. Inflation and worker shortages have forced many daycares in the state to raise their prices. As a result, care for a 4-year-old costs an average of $800 per month, which is out of reach for many families. To help you understand the child care landscape in Texas, we’ll explain why costs are surging and cover financial strategies to help you cope.

Why the Average Cost of Daycare in Texas Is Skyrocketing

Population Growth 

Population Growth
Image Source: Pexels

Population growth is one of the reasons why the average cost of daycare in Texas is skyrocketing. From April 2020 to July 2023, the state’s population grew 4.7%, with many families relocating to major cities like Dallas and Austin. Newcomers have increased the demand for child care, and unfortunately, there aren’t enough child care providers to go around. 

Child Care Deserts 

Child Care Deserts
Image Source: Pexels

As mentioned above, Texas is experiencing a shortage of childcare providers. In fact, more than half of Texas counties have become child care deserts. In these areas, there are three times as many children under 5 than the number of daycare slots available. Due to this shortage, many parents are forced to stay at home with their kids instead of working. It’s estimated that lack of child care costs the state over $11 billion in lost productivity. 

Staff Shortages

Staff Shortages
Image Source: Pexels

Daycare centers have a difficult time finding qualified staff, which limits the number of children they can safely accommodate. According to the Texas Legislative Study Group, low wages may be contributing to staffing challenges. On average, daycare workers in Texas are paid just $11.43 per hour, well below the national average of $14.60 per hour. As a result, daycare centers have trouble attracting workers, and the industry has high employee turnover rates. Unfortunately, these staffing shortages have driven up the average cost of daycare in Texas to a level that’s unaffordable for many families. 

High Operating Expenses

High Operating Expenses
Image Source: Pexels

Daycares have high operating expenses, which is why they often can’t afford to provide competitive salaries. Despite low wages, labor costs still account for 80% of the average child care center’s budget. Daycares also spend heavily on nutritious meals and enrichment activities, leading to slim profit margins. Many child care centers have been forced to close due to insufficient revenue. Between March 2020 and January 2023, 5,000 child care providers shut their doors. 

Loss of Funding 

Loss of Funding
Image Source: Pexels

Unfortunately, loss of pandemic-era funding may increase the average cost of daycare in Texas even more. In 2026, daycares will stop receiving federal stimulus funding. Since these funds are helping offset high operating costs, daycares may be forced to raise their prices when the stimulus ends.

How to Cope with Rising Daycare Costs

The average cost of daycare in Texas can feel downright unaffordable. Here are some financial strategies you can implement to help your family cope. 

The Texas Workforce Commission

The Texas Workforce Commission
Image Source: Pexels

The Texas Workforce Commission provides child care scholarships for eligible children under 13 to allow parents to attend work or school. TWC’s Child Care Management Services requirements differ from county to county, and applicants have to pass an eligibility screener.  Once approved, these scholarships can cover a portion or all of the costs associated with child care. Their website can help you identify local service providers who accept the benefits. 

Taxes

Taxes
Image Source: Pexels

The Child and Dependent Care Credit is a tax break that can offset the cost of daycare. The tax credit can be applied to 20-35% of qualifying daycare expenses, helping to relieve some of your financial burden. However, you must be a working parent or looking for a job to qualify, and the tax credit may be smaller for higher-income families.

Flexible Spending Accounts

FSAs help with the average cost of daycare in Texas
Image Source: Pexels

Your employer may offer a Dependent Care Flexible Spending Account, which allows you to set aside pre-tax dollars for child care costs. However, there’s a limit to how much you can contribute to an FSA. Single-filers can only deposit up to $5,000 per year even if the amount they spend on daycare is higher.

How do you cope with the cost of daycare? Share your tips in the comments.

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: cost of day care, daycare, money

10 Times Kids’ Stupid Mistakes Wrecked Their Parents’ Finances

February 14, 2025 | Leave a Comment

Kids mistakes that wreck family finances
Image Source: Pexels

Some types of kids’ mistakes are easy to laugh off, such as the DIY haircuts children give each other when they discover the kitchen shears. However, other mishaps and accidents can have real financial consequences for families. For example, parents may be saddled with serious costs if their kids cause property damage at a neighbor’s house or make unauthorized, nonrefundable purchases. To help make you aware of potential financial risks, here are 10 common kids’ mistakes that could cost you serious money. 

10 Kids’ Mistakes That Cost Their Parents Serious Money

1. Game Microtransactions

Gaming microtransactions
Image Source: Pexels

One of the most common and costly kids’ mistakes is game microtransactions. Over the years, there have been many reports of children buying thousands of dollars of in-game content. For example, a six-year-old in Connecticut racked up a $16,000 bill in a mobile game called Sonic Forces: Speed Battle. His mom initially noticed the problem after $2,500 was charged to her credit card. 

However, when she contacted her credit card company, she was told that the charges were probably fraud-related. Because she believed she was being scammed, she didn’t question her son about the charges, which continued to mount. 

By the time everyone realized what was happening, her son had run up a $16,000 bill. Unfortunately, the 60-day refund window had passed, leaving her responsible for the microtransactions. Yikes! 

To prevent this from happening to you, remember to enable parental controls that block in-app purchases and remove your credit card information from your devices. 

2. Property Damage 

Kids’ mistakes can also cause extensive property damage. Football star Tyreek Hill’s South Florida home, which he purchased for $6.9 million, was damaged in an accidental fire. Reportedly, a child playing with a lighter in one of the bedrooms started the blaze, which primarily engulfed the attic. Luckily the family made it out safely and no one was injured. 

Although insurance covers property damage, homes hold many sentimental memories and belongings that often can’t be replaced. So it’s tragic when children’s unintentional mishaps cause fires. 

3. A $4,000 Amazon Order 

Amazon orders can be kids mistakes
Image Source: Pexels

Nowadays kids are so tech-savvy that a 5-year-old figured out how to place a massive Amazon order, costing her parents thousands. According to Today.com, Lila asked her mom for her phone one night to play some games. But instead, Lila actually logged into Amazon and went on a huge shopping spree. 

She bought nearly $4,000 of merchandise using a saved credit card, including multiple dirt bikes and pairs of women’s cowboy boots. Her mom canceled the orders that hadn’t shipped yet, but several huge boxes still showed up at their door a few days later. 

Fortunately, this was one of the kids’ mistakes that was reversible. All of the Amazon sellers agreed to take back the merchandise and issue refunds. Some parents aren’t so lucky and end up saddled with unreturnable products. 

When Lila’s parents asked why she pulled this stunt, she simply said “I wanted it and I got it.” Hopefully, this sassy little shopper has learned her lesson and won’t put her parents in financial jeopardy again! 

4. Roughhousing 

Another common kid mistake is roughhousing. Children can get carried away while playing and forget their own strength, which sometimes results in injuries. If you leave your child unsupervised and cause harm to a peer, you could be responsible for the injured party’s medical bills. However, there are usually caps on how much money parents can be held liable for. 

5. Unauthorized Donations 

Tweens and teens have also made costly kids mistakes that messed up their family’s finances. According to Screen Rant, one teenager donated nearly $20,000 of his family’s savings to popular Twitch streamers. Luckily the parents were able to contact Twitch’s payment processor and get the vast majority of the money refunded. 

However, the situation was a big logistical headache. It was hard to get in touch with anyone who could help, and some of the funds couldn’t be recovered, causing financial losses. Although this teen definitely should’ve known better, younger children also use Twitch, so parents argue that the platform needs better fraud detection methods. 

6. Memecoins 

Memecoin kids financial mistakes
Image Source: Pexels

Another financial kids’ mistake parents should be aware of is selling memecoins. These are cryptocurrencies that are created for fun or as a joke. One teen made his own memecoin and bought a large percentage of the shares. 

Unexpectedly, the coin surged in value, prompting the teen to cash out and earn tens of thousands of dollars in an evening. However, many other investors lost money on the coin because the teen sold his entire supply at once, causing the value to plummet. Although this incident didn’t cost his parents any money, they received angry messages on social media from disgruntled investors. 

Kids can easily be convinced to create or buy memecoins and end up on the losing end of the transaction. So make sure to closely monitor your child’s online activity so they don’t get taken in by crypto schemes. 

7. Accidental Cable Purchase

Did you ever buy a pay-per-view movie without your parent’s permission? Even today, kids are still making unauthorized cable purchases, including a 2-year-old who accidentally bought an NBA League Pass. 

While playing with the remote, she clicked just the right combination of buttons to purchase a pricey $200 cable add-on. Sadly, her dad wasn’t able to get the charge reversed, leaving him on the hook for a hefty unexpected expense. To prevent future mishaps, he added password purchase protection to his TV. 

8. Online Auction Gone Awry 

Online auctions kids bidding
Image Source: Pexels

Kids can also get into trouble with online auctions. A 14-month-old little girl gained access to her father’s eBay account on his phone. She placed a bid on a vintage car and ended up winning the auction for $225. Her dad’s first reaction was to panic and ask the seller to cancel the transaction. 

Although the seller was willing to release him from the deal, he ended up deciding to keep the vehicle. He started working on it as a project car and hopes to give it to his daughter when she’s old enough to drive. While this purchase didn’t necessarily wreck her family’s finances, the car repairs will likely cost them thousands, making it an expensive kids’ mistake.

9. Damage to Neighbor’s Property 

Another common kid mistake that puts strain on the family’s finances is vandalism. Some children act out their frustration on others’ property, resulting in hefty bills for their parents. One Reddit user’s glass greenhouse was broken by an unruly neighborhood child, resulting in nearly $3,000 in damages. 

10. Huge DoorDash Orders

Kids mistakes DoorDash
Image Source: Pexels

The final kid mistake we want to highlight is placing an accidental food order. A Texas mother left her phone unlocked, allowing her 2-year-old son to gain access to her DoorDash account. Somehow he clicked the right combination of buttons to order 31 cheeseburgers from McDonald’s. He also left a generous 25% tip for the driver, which brought the total to a whopping $91.70. 

His mom said the incident was funny because no one in the family likes cheeseburgers. She made a post on a local Facebook page to explain the saga and offer up the burgers for free. Her story ended up going viral and was even covered by CNN.

Have your children ever made any mistakes that had negative financial consequences? Share your stories in the comments.

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: Kids, money, playtime disasters

Daycare Vouchers in Florida: 7 Things You Need to Know to Apply Today

February 7, 2025 | 2 Comments

How to get daycare vouchers in Florida
Image Source: Pexels

If you’re struggling with the high price of childcare, you may be wondering how to get daycare vouchers in Florida. The annual cost of daycare in the state tops $9,000, so many parents and guardians need assistance to be able to afford it. That’s where the School Readiness Program comes in, which provides childcare subsidies based on your household size and income level. Here are 7 things you need to know about the process to apply today.

How to Get Daycare Vouchers in Florida 

Answering your questions about how to get daycare vouchers in Florida
Image Source: Pexels

Understand the Program 

Before we dive into how to get daycare vouchers in Florida, let’s go over how the program works. Childcare assistance is usually provided through the School Readiness Program. It helps families of kids aged birth to five afford childcare by offsetting the cost. You’ll still be responsible for a copay (check out a sample fee schedule here), which varies depending on factors like the county you live in and the age of your child. But the copay is much more affordable than the full, unsubsidized price of daycare. 

Determine Your Eligibility 

Wondering how to get daycare vouchers in Florida? First, you need to determine whether or not your family is eligible for assistance based on your income and number of children. To qualify for subsidies, your earnings must be at or below 150% of the federal poverty level for a household of your size. This FPL calculator can help you figure out where your family stands. 

Additionally, there are work requirements parents and guardians have to meet. You must be employed at least 20 hours per week or attend school and take 12 or more credit hours to qualify. 

Submit Your Application 

Here's how to get daycare vouchers in Florida
Image Source: Pexels

Applications for the School Readiness Program are handled by each county’s Early Learning Coalition. You can use this directory to find your ELC’s location and contact information. Many offices allow you to apply for the program in person. But you can also submit your application online through Florida’s Early Learning Family Portal. Don’t forget that there are a few required documents you must send in with your paperwork, including your child’s birth certificate and proof of income, residency, and employment or school enrollment.

Waiting Lists

Sometimes there’s too much demand for childcare assistance at once. When this happens, the county starts a waitlist and ranks families based on factors like the application date, the age and ability of the child, and the level of financial need. The ELC often prioritizes at-risk children and kids with special needs. 

It’s important to note that once you’re on a waiting list, you must revalidate your information every 6 months to renew your spot. You’ll be notified 30 days before your revalidation is due. Failure to provide information can result in your removal. A subsequent application would put you further down the list and force you to wait longer, so be sure to respond to requests for documentation!

Choose an Approved Daycare Provider

Daycare assistance
Image Source: Pexels

The School Readiness Program requires you to choose a state-approved childcare provider to receive the subsidy. The Department of Children and Families has a provider lookup tool that can help you find a reputable daycare for your child. Simply enter the name of your city to pull up a directory of trusted providers in your area. The tool can also be used to vet childcare centers that friends and family recommend by inputting their names. You can contact your local Child Care and Resource agency if you need further assistance with finding an approved daycare. 

Renewals

Florida’s Daycare Vouchers are not permanent and must be renewed every time the benefit expires, which is often every 12 months. Going through a renewal is very similar to the original application process. About a month before your benefit ends, the state will notify you of the information they need. The state is looking to confirm that you and your family still qualify for benefits and will request a number of documents to prove your income and your education or employment status.

Eligibility Changes 

How to get daycare voucher in Florida if eligibility changes
Image Source: Pexels

Once you’re enrolled in the program, you must report any changes that could affect your eligibility, such as a salary bump. Your ELC should have an eligibility change form available on their website that you can fill out and send in. If you need to take a break from the program temporarily or change providers, you’ll also have to notify your ELC. 

Still stuck? Your local Child Care and Resource Referral can answer your questions about how to get daycare vouchers in Florida.

If you’ve been through the process, share your experience in the comments to help other parents! 

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Parenting Tagged With: Childcare, Kids, money

Here’s Everything You Should Know About The New Child Support Bill

February 3, 2025 | 7 Comments

Here's Everything You Should Know About The New Child Support Bill Key
Image Source: Pexels

It’s only February, but a new child support bill has already been passed, and another has been proposed. With all of these legal changes, it is important to understand what is new for 2025 and what could be coming down the road. Here’s an overview of the impacts of the new child support bill.

New Child Support Bill

New Child Support Bill
Image Source: Pexels

On January 4th, President Biden was presented with and signed the Supporting America’s Children and Families Act. Originally introduced to the House of Representatives in July of 2024, the SAC&F Act primarily focuses on supporting vulnerable children in foster care through Title 4 Social Security assistance. The new law also impacts child support and the ability of states to collect it. While the original bill passed in the House had a number of other measures centered on delinquent child support, those provisions seem to have been lost in the Senate.

The major impact of the SAC&F Act on child support is allowing states to use contractors to collect overdue payments through federal tax refunds. Plus, the bill expanded Native American tribal access to tax information, enabling them to run their own independent child support enforcement programs. This legislation will help ensure that caregivers receive the child support payments they rely on to make ends meet. It will also make it harder to evade child support.

The use of contractors to collect payments is expected to be a cost-saving measure, bringing in $5 for every dollar spent. The Congressional Budget Office has estimated the savings from the new child support bill will be nearly $800 million dollars.

Potential New Child Support Bill Introduced

Potential New Child Support Bill Introduced
Image Source: Pexels

In late January, Senator Kevin Cramer of North Dakota introduced a new child support bill. If passed, it would allow soon-to-be mothers to receive child support before giving birth. While Cramer is a conservative lawmaker, similar measures have been enacted by states across the political spectrum, from California to Alabama.

Currently, 25 states including North Dakota have enacted the Uniform Parentage Act. It was originally introduced in 1973 and gives women a legal mechanism to file for and collect child support while pregnant. If passed, Cramer’s bill would give this ability to women in every state.

In states without the Uniform Parentage Act, mothers are only eligible to collect child support after giving birth. This places the full financial burden of pregnancy, which can cost $19,000 on average, solely on the mother. While Cramer’s bill has the potential to be bipartisan, there are possible issues with blanket implementation on the state level.

Potential Ramifications

A requirement of child support is first determining paternity. Some states require that when a married woman is pregnant, the husband is automatically listed as the father. This legally establishes paternity even if there is a separation, pending divorce, or infidelity. The paternity could later be challenged and determined via DNA testing. However, this could leave uninvolved husbands temporarily responsible for child support in states that use marriage to determine paternity.

However, there’s no reason to worry about this bill’s potential ramifications yet. Cramer’s bill still has a long way to go before being made law. It was only introduced last week, so it still needs to be introduced and voted on in the House. As we’ve seen with the Supporting America’s Children and Families Act, there can be numerous revisions throughout this process. And if the bill were ultimately passed, it could look significantly different than the original proposal.

What do you think of the changes brought about by the new child support bill? Let us know in the comments.

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: child support, Kids, money

5 Characteristics of a Good Parent for Raising Financially Savvy Kids

January 17, 2025 | Leave a Comment

5 Characteristics of a Good Parent
Image Source: Pixels

If you want your kids to grow into financially savvy adults, it’s important to start educating them about money early on. However, teaching kids about money isn’t easy and requires these 5 characteristics of a good parent. Money is an abstract concept that can be hard for kids to grasp, so it takes a special approach to instill good financial values. Here are some tips to help you pass down financial knowledge to the next generation.

Raising Financially Literate Kids: 5 Characteristics of a Good Parent

Here are the 5 characteristics of a good parent
Image Source: Pexels

Creative

Some kids aren’t interested in money, so may need to find creative ways to get your children excited about finances, such as play-based learning. For example, running a pretend grocery store can help young children understand the cost of food and the purchasing power of money. Older kids may enjoy playing family board games like PayDay, Monopoly, and The Game of Life, which impart crucial financial lessons. 

It’s also important to find creative ways to instill good financial habits. Providing your kids with opportunities to earn an allowance can teach them the value of hard work. To motivate them to start building a nest egg, consider matching a percentage of their savings. You can also encourage them to set financial goals and help them make a plan to achieve their savings targets. You could even do a no-spend or pantry challenge as a family to make saving money fun. 

Honest

Honesty is one of the 5 characteristics of a good parent
Image Source: Pexels

Opinions vary on whether or not you should discuss the household budget with your kids. Some parents believe that exposing kids to adult money matters could stress them out. However, others argue that shielding your children from financial realities like bills and debt leaves them unprepared for an independent life. 

Luckily it’s possible to strike a balance between the two. You can be honest about your financial situation without overwhelming your kids by keeping the discussion age-appropriate. Younger kids can handle being told that the toy they want isn’t in the budget right now. Tweens and teens may be ready for conversations about tougher topics in preparation for adulthood, such as student loans and job loss.

Responsible

Model good financial behavior
Image Source: Pexels

Next on our list of 5 characteristics of a good parent is responsibility. You can’t expect your kids to become financially savvy if you aren’t prudent with your own money! It’s important to model positive financial habits like paying bills on time, avoiding debt, saving and investing regularly, and practicing frugality. 

Although your kids will learn just by watching you, try getting them involved in the process of running a thrifty household. For example, you can clip coupons together and explain what sales circulars are. Teach them how to compare the unit prices of products at the supermarket and find the best deal. It’s also wise to pass down practical, money-saving skills they’ll need in adulthood, such as cooking and home improvement. 

Entrepreneurial and Adaptable

Entrepreneurial mindset is one of the 5 characteristics of a good parent
Image Source: Pexels

Young adults often rely on side hustles to get by, including 70% of recent college grads. For that reason, it’s essential to teach your kids to be adaptable and entrepreneurial. You can encourage your child to develop a business mindset by helping them identify earning opportunities, such as babysitting or selling their art. You can also lead by example and work on developing multiple streams of income to build financial resilience.

Patient 

Being patient with kids is important
Image Source: Pexels

Last but not least, patience is one of the 5 characteristics of a good parent who’s raising financially savvy kids. Money is a complex subject, so children usually need lots of repetition to wrap their heads around it. You might have to teach them the same money lesson multiple times for it to really sink in. Explaining abstract concepts like compound interest and index funds could take a while, so remember to be patient with your kids while they learn the ropes. 

As they grow and begin to spread their wings, they may make some financial mistakes. Instead of shaming them, help them understand where they went wrong in a nonjudgmental way. Providing gentle correction when they mess up (and positive reinforcement when they succeed) will help guide them toward the right financial path. 

How do you teach your kids financial literacy? Share your tips in the comments!

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: education, money, Parenting

Trust Fund for Kids: Mistakes to Avoid When Securing Their Future

January 3, 2025 | Leave a Comment

Trust funds for kids
Image Source: Pexels

A trust fund for kids can be a useful financial tool that helps set your children up for success. Inherited wealth can sometimes be spent unwisely due to immaturity or lack of financial education. Distributing your assets to your kids through a trust gives you greater control over how the money is used, ensuring generational wealth isn’t wasted. A trust fund for kids can also be put in place to provide for children with special needs. However, the trust may not have the intended effect if it’s set up improperly. It’s important to avoid common pitfalls when securing your child’s future with a trust. Here are common mistakes parents make when setting up a trust fund for kids. 

Setting Up a Trust Fund for Kids: Common Pitfalls 

Common mistakes when setting up a trust fund for kids
Image Source: Pexels

Not Understanding the Different Types of Trust Funds for Kids

There are two main types of trusts—revocable and irrevocable. A revocable trust can be changed after it’s established, allowing for greater financial flexibility. Irrevocable trusts, on the other hand, usually can’t be amended once they’re set up. However, they often provide more protection from lawsuits and creditors while offering certain tax benefits. 

For example, a generation-skipping trust enables you to pass down money to your grandkids to avoid estate taxes. If you’re setting up a trust for a disabled child, a special needs trust can help ensure they remain eligible for certain government benefits. Figuring out which trust fund for kids is right for your family is a crucial step in the process, especially since irrevocable trusts cannot easily be modified. 

Choosing the Wrong Trustee 

Choosing the wrong trustee
Image Source: Pexels

Parents setting up a trust fund for kids must choose a trustee to manage and disburse the assets according to the rules they set. The trustee will have control over your wealth, so it’s important to choose someone responsible who will invest it wisely. Although you love your family members and friends, it’s possible that they may not be the best choice for this role. Naming a relative as a trustee can put them in the awkward position of having to deny your child access to funds at times. Mixing family and finances in this way could put a strain on your child’s relationships.  

Choosing a professional fiduciary like a bank to be the sole or co-trustee may be a better move depending on your circumstances. As a neutral third party with significant financial expertise, your bank can help ensure your wealth is protected and distributed according to your wishes. However, financial institutions usually charge management fees, which is something to consider. Before you make any decisions, be sure to carefully research and weigh your options. 

Setting Overly Rigid Rules 

Overly rigid rules trust fund for kids
Image Source: Pexels

Trust funds can be used to incentivize your kids to make good decisions. Some parents choose to set rules that reward positive behavior. For example, a child who maintains a great GPA in college may be allowed access to a bigger portion of the funds at an earlier age. You can also tie disbursements to major life milestones, such as getting married or buying a house. However, setting rules that are too rigid could prevent your child from accessing needed funds. After all, life can take many twists and turns, so it may be unwise to tie their inheritance to specific life benchmarks like marriage or college graduation.

It’s important to consider your child’s abilities and goals when setting guardrails. In some cases, it may be better to schedule disbursements according to your child’s age instead of their specific life stage. This setup ensures that your child is mature enough to handle the financial responsibility of managing their inheritance while providing greater flexibility. Another option is to require your adult child to meet with a financial advisor before gaining control of the funds. Your lawyer can help you structure the trust with rules that will set your child up for financial success without being overly strict. 

Failing to Consider the Impact on Financial Aid

Trust fund for kids can impact financial aid
Image Source: Pexels

Parents creating a trust fund for kids must also consider the impact on college scholarships and financial aid. If your child is named as the beneficiary, the trust fund will typically be counted as one of their assets. Depending on the value of the trust and how it’s structured, it could affect their eligibility for financial aid. It’s important to consult your lawyer to determine how distribution rules and other factors could impact your child’s education. 

Trust Funds for Kids Can Be Complicated

Trust funds for kids are complex
Image Source: Pexels

Although trust funds are a valuable financial planning tool, they can be quite complex. That’s why it’s important to consult lawyers and other experts you trust during the setup process. Taking the time to fully understand and carefully consider your options will prevent you from making costly mistakes. 

Vicky Monroe headshot
Vicky Monroe

Vicky Monroe is a freelance personal finance writer who enjoys learning about and discussing the psychology of money. In her free time, she loves to cook and tackle DIY projects.

Filed Under: Money and Finances Tagged With: child trust fund, Kids, money

How Much Does Unschooling Cost?

August 12, 2021 | Leave a Comment

Unschooling Costs

Homeschooling can take many different forms, from essentially recreating school at home by using workbooks and taking multiple tests to a Charlotte Mason method where children derive their education largely through reading living books. There is also the Classical Education philosophy based on learning the classics like Greek and Roman history and language. However, perhaps the most misunderstood homeschool philosophy is unschooling. While detractors say unschooling isn’t really schooling at all, unschoolers see it as a viable educational form. If you’re interested in unschooling, you first must understand what the philosophy is and how much unschooling costs.

What Is Unschooling

Unschooling is an educational philosophy. Unschoolers don’t typically have their children take standardized tests or any other test. They don’t use textbooks or follow a set curriculum. Instead, the child determines what he would like to study based on his interests.

Cooking, gardening, and raising animals can all be part of the school day for an unschooler. Unschoolers also may code a robot, research the Titanic, do a science experiment, or record a new YouTube video all in the name of school. The idea is that unschoolers will learn more deeply because they’re working on things that interest them and that they choose to pursue. Hopefully, this helps the child become a lifelong learner.

However, critics argue that unschooling does not lead to a well-rounded education necessary for adult life. If an unschooler is not interested in math, she may not study it, which could cause problems in adulthood. Similarly, one who is interested in science may not study writing because she’s not particularly strong in that area.

How Much Does Unschooling Cost?

Unschooling costs can vary widely depending on the amount of money the parent has to dedicate to unschooling and the child’s interests.

Ways to Unschool for Free

If you don’t have much money to dedicate to unschooling, that’s okay! You can still give your child a stellar education. Consider these opportunities:

The Library

The library offers many educational items for your child from library books to movies to foreign language learning programs. In addition, most libraries offer regular learning programs such as wildlife experts who bring animals to the library or scientists who teach astronomy. Most libraries also offer activities like chess club and teen time that your child can join.

The Outdoors

Unschooling Costs
Photo by David Clode on Unsplash

One of the greatest classrooms is the great outdoors. Give your child ample time to hike and take nature walks. Some children enjoy keeping a nature journal. They can search for animals, observe the seasonal changes, watch birds. . .the possibilities are endless.

The Internet

There are some high-quality educational services on the Internet.

EdX

EdX offers free online college classes from 160 universities including Harvard, MIT, Boston University, and the University of California, Berkeley, to name a few. You can study architecture, math, literature, engineering, food and nutrition, and many more subjects with some of the greatest minds in the United States.

YouTube

If you think of YouTube as a place to waste time, think again. You can find tutorials and even educational lessons. My daughter and I are studying Japanese, in part through YouTube lessons that we find.

If You Have Money to Spend

If you have more money to spend on unschooling, you can take advantage of other academic resources.

Camps

Educational camps offer your child a unique way to learn. There are science camps, sports camps, liberal arts/reading camps. You can find what you need for your child if you have the money to pay for it.

Subscriptions

Likewise, you can also take advantage of subscription services to help your child in her educational endeavors.

Magazine Subscriptions

Magazine subscriptions from National Geographic to LEGO Magazine to Architectural Digest may feed your child’s desire to learn more about their current unschooling interests.

Box Subscriptions

Likewise, box subscriptions can also help spark your child’s creativity. Some of the most popular educational subscription boxes include Kiwi Crate for science and art, Atlas Crate for geography and culture, Tinker Crate for science and engineering, and Eureka Crate for engineering and design.

If your child is more creative, there are I Create Art boxes for budding artists. Young chefs may enjoy Eat2Explore cooking boxes.

For most interests a child can have, you can find a subscription box.

Tools & Learning Aids

If you have a budding scientist, and you can afford to buy a student microscope, your child can spend time creating slides and looking under the microscope.

How Much Does Unschooling Cost?
Photo by Simon Delalande on Unsplash

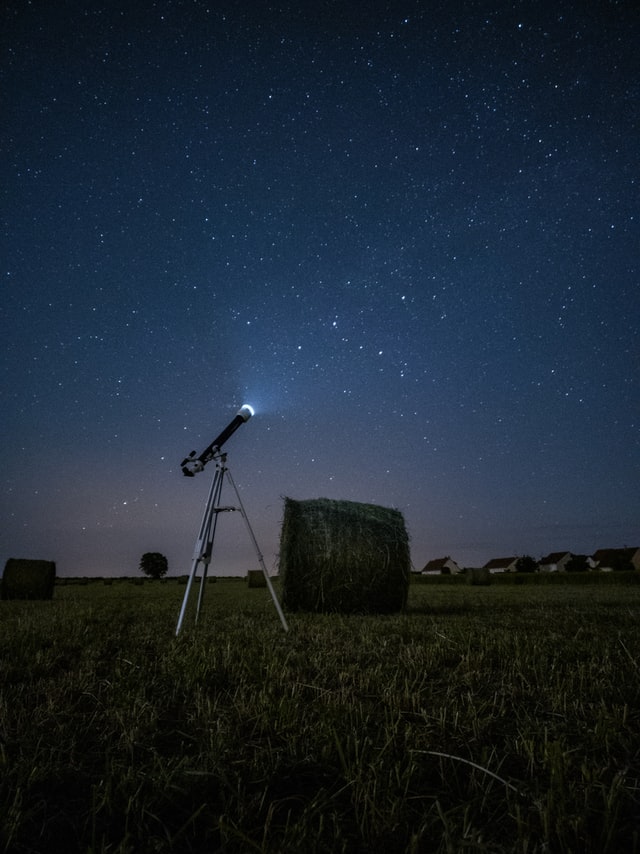
You might buy a telescope for a child who is interested in astronomy or ample art supplies for a student who is interested in art.

A child who is interested in chemistry might benefit from a chemistry science kit. A history buff may want to take field trips to historic sites and museums to learn more.

If Money Is Available but Limited

Most of us aren’t independently wealthy. If you have some money to spend on your child’s education, but that money is limited, consider handing over control to your child. Let’s say you have $3,000 a year to spend on your child’s education. You can give your child $750 per quarter. Then, she can decide how to spend the money on her education each month.

If you feel comfortable letting her have this control, you are embracing the philosophy of unschooling as a child-lead schooling option. Plus, just letting her choose what to buy and deciding if the items were worth the money is an educational experience in itself. She’ll also learn how to budget the money. If she wants to attend an expensive camp in the summer, she’ll need to save the money from previous quarters to afford the camp.

Final Thoughts

Unschooling is a controversial form of homeschooling, but many unschoolers have gone on to be successful adults. If you opt for this form of homeschooling, know that unschooling costs as little or as much as you want it to.

Read More

What You Need to Know to Homeschool Your Child in the Age of Covid-19

How to Choose the Right Homeschooling Curriculum for Your Star Student

Where to Find Food If Your Children Are Going Hungry

What to Do if You Forgot to Cancel a Trial Subscription

Melissa Batai
Melissa Batai

Melissa is a writer and virtual assistant. She earned her Master’s from Southern Illinois University, and her Bachelor’s in English from the University of Michigan. When she’s not working, you can find her homeschooling her kids, reading a good book, or cooking. She resides in Arizona where she dislikes the summer heat but loves the natural beauty of the area.

Filed Under: Education, Money and Finances Tagged With: education, Homeschool, money, unschool

What Age Should Kids Learn About Money?

February 8, 2021 | Leave a Comment

Kids Learn about Money

What age should kids learn about money?  That’s a difficult question because kids learning about money isn’t the same as, say, potty training.  Kids continue to learn about money throughout their childhoods.  However, having said that, your kids can begin to learn about money in the early preschool years and continue on from there.

How Preschool Kids Learn about Money

At this age, kids are watching you closely so set a good example.  For instance, when you go to a grocery store, don’t reward your kids with a treat every time.  If you do, they start to expect that you will just buy things for them.

Instead, create buy, spend, and save jars.  If you want to pay them an allowance for chores, now is the time to start.  You can set up a chore chart, and pay them for their chores.  When you pay them, you can help them separate their money into the three jars.  Let them use their spend money for little things they want to buy.

This is also a good time to get them money-related toys like play cash registers so they can get used to the concept of the different values of our coins and bills, spending money to buy something, not having enough money, and making change.  Play store and grocery shopping with them frequently.

How Elementary Kids Learn about Money

Once your children learn the rudimentaries about money, it’s time to teach them more complex lessons.  The grocery store is a great place to teach these lessons.  You can teach about buying generics, price comparing different sizes of the same product, and the value of using coupons.

Kids this age will be earning more than they did as preschoolers, so you can also help them save for a large goal like an expensive Lego set they want to buy.  You should also teach them that once the money is spent, it’s gone.  Then, they need to work hard to earn more to save and spend all over again.

How Middle School Kids Learn about Money

At this age, kids are going to want to spend, spend, spend.  This is the time to teach them, if you haven’t already, that you won’t buy everything they want.  Just because your daughter wants new jeans when she already has enough doesn’t mean you’ll buy them.  She can save her money and buy them if she really wants them.

You should also teach them about the power of compound interest.  This helps them realize that if they delay spending today, compounding interest can help them have more money later.

How High School Kids Learn about Money

Now is the time when all your hard work teaching your kids about money comes to fruition.  Rather than buying or giving your child a car, have them save for at least half of the price of a car.

Also, teach your kids about credit cards, how to use them responsibly, and how to avoid accruing debt.

Be very clear how much you can afford to pay for their upcoming college.  Then, they can choose a college that is affordable, or choose one that costs more than you can afford.  However, help them understand how accruing student loan debt can make it harder to achieve their goals in adulthood.

Final Thoughts

Throughout your child’s life, you should be teaching them money lessons.  As they age, these financial lessons should become more specific.  If you’ve done your job well, by the time they leave home, they’ll be able to make smart money decisions.  However, if your child makes foolish money decisions, know that you’ve laid the ground work so they know how to improve their financial situation should they need to.

Read More

Teach Your Child About Money–Free Savings Chart for Kids

Parenting Win–Teaching Money Skills to Your Kids

Games That Teach Kids about Money

Best Places To Sell Rare Pennies


Melissa Batai
Melissa Batai

Melissa is a writer and virtual assistant. She earned her Master’s from Southern Illinois University, and her Bachelor’s in English from the University of Michigan. When she’s not working, you can find her homeschooling her kids, reading a good book, or cooking. She resides in Arizona where she dislikes the summer heat but loves the natural beauty of the area.

Filed Under: Education, Parenting Blog at KidsAintCheap Tagged With: Counting money, money

Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Baby

9 Baby Names Inspired by Fall Without Naming Your Child Autumn

Evan Morgan
Baby

10 Vintage Baby Names That Sound Surprisingly Modern Again

Evan Morgan
Baby names

Teachers Admit: These 6 Baby Names Create Instant Bias in the Classroom

Latrice Perez

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette