• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

Kids Outgrow Clothes Fast — But These 7 Things Shouldn’t Be Bought Used

September 28, 2026 | Leave a Comment

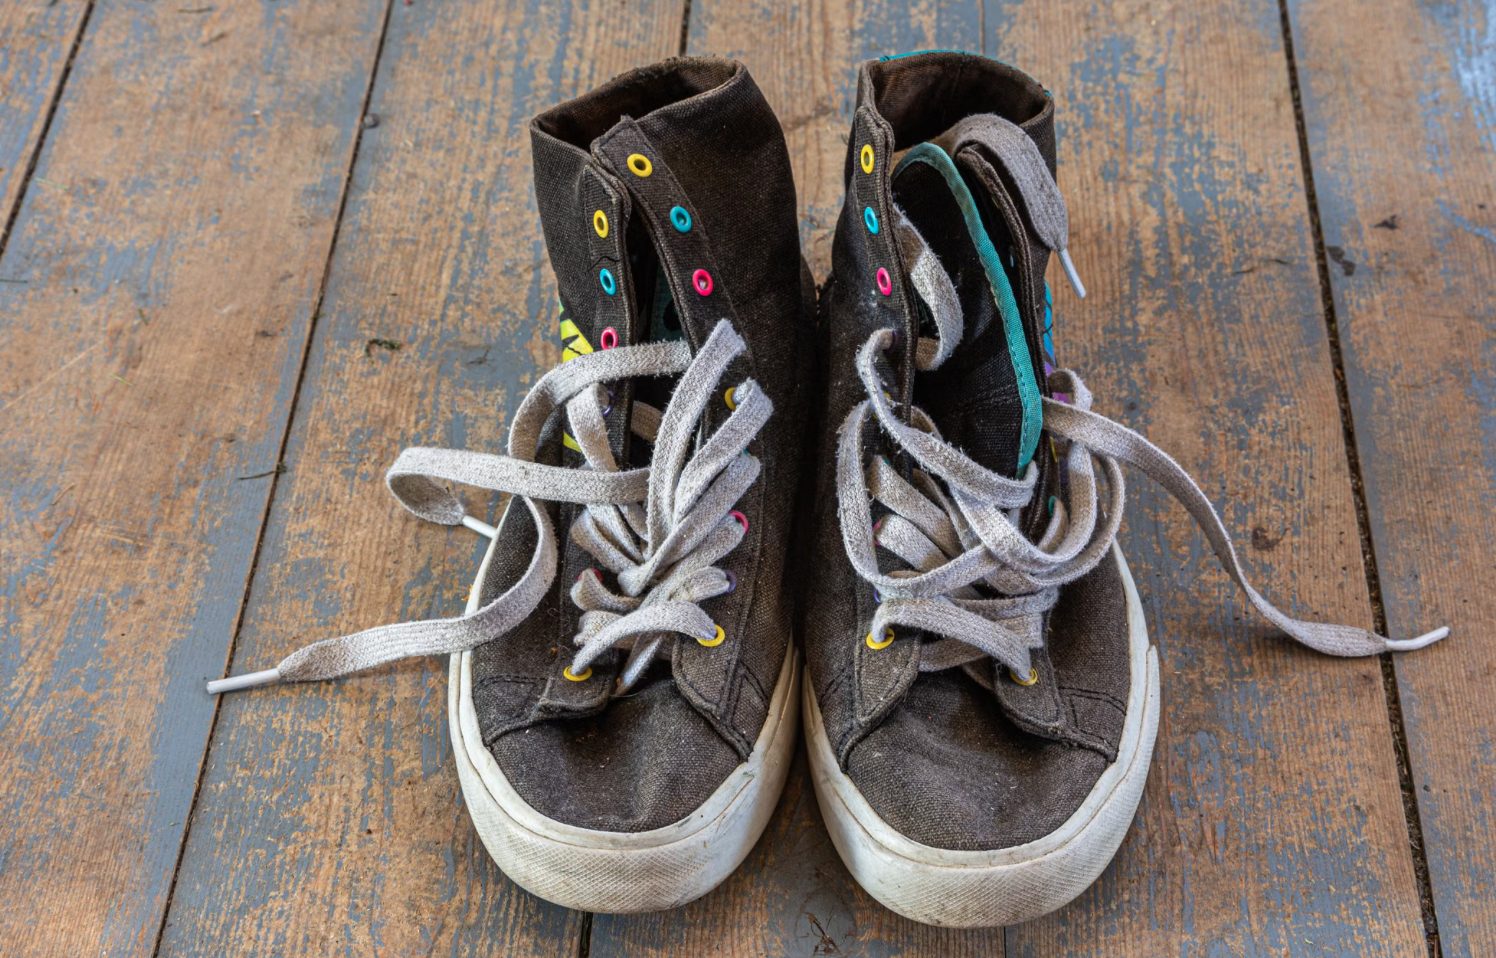
Kids Shoes
Secondhand clothing can stretch a family budget, but safety-sensitive products such as car seats, helmets and sleep gear require more caution. Knowing what to buy new can prevent a bargain from becoming a costly mistake. (Pexels).

Anyone raising children knows how quickly perfectly good clothes can become too small. Buying secondhand can be a smart way to stretch a family budget, particularly when many shirts and jeans are barely worn before they are outgrown. In 2026, the National Retail Federation reports that K-12 families expect to spend an average of $250.29 on clothing and accessories and another $174.01 on shoes. National Retail Federation That makes used kids items tempting, but some purchases carry risks that a bargain price cannot reveal.

1. Car Seats With An Unknown History

A used car seat can look spotless while hiding damage that cannot be seen from the outside. Consumer Reports notes that most car seats have useful lives of roughly six to 10 years, and crash history, recalls and expiration dates all matter. A marketplace seller may honestly believe a seat is safe without knowing whether it experienced damaging crash forces years earlier. If a new seat costs $180 while a used one costs $70, that $110 savings is difficult to justify when its complete history is uncertain. Among used kids items, car seats deserve particularly careful scrutiny.

2. Bike And Sports Helmets

Helmets are another product where damage may be hidden beneath a good-looking exterior. Consumer Reports recommends replacing a bicycle helmet after a crash even when damage is not visible, because the impact-absorbing foam may already have been compromised. It also recommends replacing a well-used helmet after approximately five years. Unless you personally know the helmet’s entire history, buying new removes an important unknown. Parents can still save by choosing a basic safety-rated model instead of paying extra for graphics or a fashionable brand.

3. Cribs With Missing Parts Or Labels

That beautiful hand-me-down crib may have more history than a seller realizes. The American Academy of Pediatrics advises families using previously owned cribs to make sure they meet current standards, have proper slat spacing and are not missing hardware. Repeated assembly, disassembly, or improvised replacement hardware can also make evaluating an older crib difficult. Older models may lack instructions or identifying information needed to check their history. A dresser can be a terrific secondhand find, but an infant’s primary sleep space deserves a higher bar.

4. Used Crib Mattresses

A crib mattress is another used item where appearance does not tell the whole story. Safe infant sleep requires a firm, flat surface that fits the crib properly, and a previously used mattress can develop sagging or damaged areas. The American Academy of Pediatrics emphasizes that the sleep surface should be firm and should not indent under the baby. Stains, moisture exposure, and unknown storage conditions provide additional reasons to be cautious with mattresses from strangers. Saving elsewhere in the nursery may make more sense than gambling on the condition of a baby’s sleep surface.

5. Single-User Breast Pumps

A secondhand breast pump can seem like an easy way to avoid another large baby expense, but check the manufacturer’s designation first. Medela, for example, states that its Freestyle Mini is a single-user product and should not be borrowed or purchased secondhand, even though it uses a closed-system design. That is different from equipment specifically designed and validated for multiple users, such as certain hospital-grade rental pumps. Parents should therefore never assume that “closed system” automatically means “safe to share.” With these used items, the model’s instructions matter more than the seller’s description.

6. Heavily Worn Shoes

Shoes are trickier because experts do not universally say every lightly used pair must immediately go in the trash. However, the American Podiatric Medical Association recommends checking children’s shoe sizing every four to six months and allowing roughly 10 to 15 millimeters of room ahead of the longest toe. A used shoe may already have compressed cushioning, uneven tread, or a shape influenced by its previous wearer. That makes heavily worn athletic shoes and everyday sneakers poor places to economize. Families can instead buy fewer new pairs, measure both feet and prioritize fit over expensive logos.

7. Children’s Sleepwear With Missing Safety Information

Used pajamas may look like ordinary clothing, but children’s sleepwear is subject to special flammability requirements. U.S. rules distinguish qualifying tight-fitting sleepwear from other children’s sleepwear, making fit and labeling more important than many parents realize. Cornell Legal Information Institute provides details on the federal requirements covering children’s sleepwear. Be cautious when resale pajamas have missing labels, unclear sizing, damaged fasteners or enough stretching that formerly snug sleepwear now hangs loosely. Buying new makes it easier to verify the intended size, labeling, and condition.

The Best Bargain Is Knowing Where Not To Cut Corners

Secondhand shopping still makes excellent financial sense for many children’s shirts, jeans, coats, books and other easy-to-inspect belongings. The key is separating cosmetic wear from products whose safety depends on history, structure, hygiene or precise fit. With families budgeting $174.01 on average for K-12 shoes alone in 2026, choosing carefully matters more than simply choosing new or used every time. Before buying used items for kids, ask whether you can verify the product’s age, condition, instructions, recall history and previous use.

Which children’s products do you happily buy secondhand, and which ones will you only purchase new? Share your experience in the comments.

What to Read Next

Bought Kids’ Toys From SHEIN or Amazon? Check These New Recalls Before Playtime

8 Money Lessons Kids Can Learn From One Trip to the Grocery Store

Are Parents Buying Too Many Clothes Before Kids Actually Need Them?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Baby Gear, car seats, child safety, children's clothing, Family Budget, Kids, Money Saving Tips, Parenting, parenting tips, secondhand shopping

The First Month of School Is When Parents Discover Which Expenses They Completely Missed

September 24, 2026 | Leave a Comment

Child In School
The first school supply run is often only the beginning, as families face additional costs for lunches, activities, equipment and replacement supplies. Tracking those expenses during the first month of school can help parents build a more realistic school-year budget. (Pexels).

Parents may think the expensive part of back-to-school season ends once the backpacks are packed and the first-day photos are taken. Then September arrives with activity fees, lunch charges, replacement supplies, club dues and requests for money that never appeared on the original shopping list. Those overlooked back-to-school expenses can turn an already expensive season into a month of budget surprises. The challenge is that many costs do not become clear until teachers, coaches and school organizations settle into their routines. For families trying to keep spending under control, the first month of school can be an important financial reality check.

The Shopping List Was Only The Beginning

Families already entered the 2026 school year expecting a sizable bill, but traditional shopping captures only part of the cost. The National Retail Federation reported that families with children in elementary through high school planned to spend an average of $863.86 on clothing, shoes, supplies and electronics this year. Meanwhile, Deloitte’s 2026 Back-to-School Survey estimated spending at $557 per K-12 student using a different survey methodology, while finding that inflation-adjusted planned spending fell 6% from last year. Neither figure means every family will spend that amount, but both illustrate why additional back-to-school expenses can hurt after a major August shopping trip. Parents can protect themselves by treating the supply list as the opening estimate rather than the final school-year bill.

Activities Can Create A Second Back-To-School Bill

Sports, music, theater and clubs may require registration fees, uniforms, equipment, transportation or specialized shoes after school starts. These costs are particularly easy to miss when a child decides to join an activity only after hearing about it at school. KPMG’s 2026 Consumer Pulse survey found that seven in 10 parents planned to protect their children’s sports participation despite rising costs, showing how important activities remain even when household budgets are strained. A realistic scenario might involve a $75 registration fee, $60 pair of athletic shoes, $40 team shirt and $50 worth of equipment, creating an unexpected $225 bill for one activity. Before signing up, parents should ask whether equipment can be borrowed, uniforms can be purchased used, and additional tournament, travel or fundraising costs will appear later.

Lunch Money Adds Up Faster Than It Seems

Cafeteria spending can become another recurring expense that looks small by the day but significant by the month. The School Nutrition Association reports typical 2025-26 paid lunch prices of $3 for elementary students, $3.20 for middle schoolers and $3.25 for high schoolers, with local districts setting their own prices. At $3.25 per lunch for 20 school days, one high school student could cost a family about $65 a month, before breakfast, snacks or extra purchases are considered. Families should also check their state and district rules because some schools provide meals at no charge, while qualifying households elsewhere may need to apply for meal assistance. Reviewing cafeteria accounts weekly can prevent these back-to-school expenses from quietly becoming a larger monthly obligation.

September Reveals What Children Actually Need

Buying everything before school starts can backfire because students often discover their real needs only after spending several days in class. A teacher may require a different calculator, headphones, art materials, extra notebooks or a specific binder that was not included on an early list. That helps explain why delaying some purchases can be practical: NRF found that 47% of 2026 shoppers planned to buy only the essentials for the beginning of school and replenish supplies later. JLL’s 2026 Back-to-School Shopping Report similarly found that 28% of surveyed parents planned to reuse existing supplies, while about 21% intended to choose less expensive or more basic versions of needed items. Waiting a week or two before buying nonessential items can reduce duplicate purchases and leave room in the budget for back-to-school expenses that were impossible to predict.

Build A Buffer Before The Next Surprise

One useful strategy is to create a small “school surprises” category rather than assuming the back-to-school budget ends on the first day. Even setting aside $25 or $50 per child each month during the first semester can provide breathing room for field trips, classroom contributions, replacement water bottles, school photos or last-minute activity costs. Parents should also read school emails carefully, check online payment portals and ask older parents which expenses typically appear later in the semester. When a new charge arrives, ask whether it is required, whether a lower-cost alternative exists and whether financial assistance or a payment plan is available before paying automatically. Tracking back-to-school expenses separately for a few months also creates a much more accurate starting budget for next year.

The Real School Budget Takes A Month To See

The biggest budgeting mistake may be assuming that back-to-school expenses are a one-time shopping event instead of a stream of costs that unfolds as the school year gets underway. Current surveys show families are already shopping strategically: Deloitte found 71% of surveyed K-12 parents planned to switch brands when preferred brands were too expensive, while NRF reported 46% of shoppers who had not finished buying were waiting for better deals. That same price-conscious approach can work after the first bell by delaying optional purchases, borrowing equipment and questioning fees before automatically reaching for a credit card. After one full month, families can total everything they actually spent and use that number to build a realistic monthly school category into the household budget.

What expense surprised you most after your child returned to school this year, and what would you warn other parents to budget for? Share your experience in the comments.

What to Read Next

Sensory-Friendly School Supplies: What Helps and What Can Be Skipped

10 Places Parents Can Find Free School Supplies Before Classes Begin

A Complete Guide to Discount School Supplies for Distance Learning

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: back-to-school costs, back-to-school expenses, budgeting, education, Family Budget, Parenting, personal finance, Saving Money, school expenses, school supplies

8 Money Lessons Kids Can Learn From One Trip to the Grocery Store

September 23, 2026 | Leave a Comment

Mom And Daughter Grocery Trip
A simple grocery trip can teach children how budgets, unit prices, store brands, sales, and spending choices affect a family’s money. Letting kids compare prices and track the cart total turns everyday shopping into a practical financial lesson. (Pexels).

A grocery run may feel routine, but for children, it can become a surprisingly useful financial classroom. Prices are right in front of them, choices have immediate consequences, and a shopping cart provides plenty of opportunities to discuss needs, wants, budgeting, and value. Those money lessons for kids matter when families are still watching food costs closely; U.S. grocery prices were 2.2% higher in August 2026 than a year earlier, according to the latest federal data. Instead of giving children a lecture about finances, parents can turn an ordinary shopping trip into hands-on practice they can understand.

1. A Budget Means Making Choices

Before entering the store, give your child a simple spending target, such as $75 for the items on your list. As products enter the cart, let an older child keep a running estimate using a calculator or phone. If the total approaches $75, ask what could be swapped, postponed, or removed. This makes money lessons for kids concrete because a budget stops being an abstract number and becomes a limit requiring decisions. University of Minnesota Extension recommends age-appropriate financial conversations that help young people weigh necessities against optional purchases.

2. Needs And Wants Are Different

The cereal aisle offers an easy lesson in separating necessities from extras. Your family may need breakfast food, but that does not necessarily mean buying the most expensive cereal or an additional box simply because the packaging looks appealing. Ask your child, “Do we need this, or do we just want it?” Then explain that wants are not automatically bad; they simply compete with other priorities. Learning that distinction helps children understand why responsible spending involves choices rather than buying everything affordable at that moment.

3. The Lowest Price Is Not Always The Best Deal

A smaller package can have a cheaper shelf price while costing more per ounce, pound, or item. Show your child the unit-price label and compare two sizes of rice, cereal, yogurt, or another familiar product. NerdWallet recommends comparing grocery deals using unit prices rather than sticker prices alone, while Consumer Reports has likewise found that larger packages can sometimes provide better value than smaller alternatives. The hidden lesson is that “cheaper” and “better value” are not always the same thing. These money lessons for kids encourage comparison instead of automatically grabbing the lowest-priced package.

4. Brand Names Can Carry A Premium

Put a national-brand product beside the store-brand version and ask your child to compare price, size, and ingredients. Store brands reached a record $282.8 billion in U.S. sales during 2025, while their dollar sales grew 3.3%, nearly three times the 1.2% growth of national brands, according to Private Label Manufacturers Association data based on Circana research. Store brands also accounted for 23.5% of units sold in the measured market. Explain that advertising, familiarity, and packaging can influence what shoppers choose. The goal is not always to buy generic, but to decide whether a higher price delivers something your family actually values.

5. A Shopping List Protects Your Money

Making a list before shopping teaches children that spending decisions can begin before anyone reaches the store. Check the refrigerator and pantry together, then write down what is actually missing. NerdWallet recommends taking inventory first because buying something already sitting at home wastes money and can undermine a grocery budget. Let your child cross off each item while shopping and notice tempting products that were never part of the plan. This is one of the simplest money lessons for kids because it connects planning directly with spending control.

6. Small Savings Can Become Real Money

Coupons, loyalty discounts, sales, and store brands may save only a dollar or two at a time, but repeated savings add up. Suppose your family trims just $8 from its weekly grocery bill through thoughtful substitutions; over 52 weeks, that equals $416. Store-brand products are now found in about 90% of grocery shoppers’ homes, according to a 2025 FMI survey of nearly 1,500 U.S. grocery shoppers. Ask your child what $416 could accomplish if saved instead of spent. That simple calculation shows why small financial decisions deserve attention.

7. Sales Only Save Money When You Need The Product

A “buy two, get one free” sign can look like automatic savings, but it may encourage a family to purchase more than planned. Ask your child whether you would have bought the product without the promotion and whether your family will use it before it spoils. A discount on an unnecessary purchase is still money leaving the household. This teaches children to evaluate promotions instead of reacting to the word “sale.” Good money lessons for kids include recognizing that spending $10 unnecessarily does not become smart simply because the regular price was $15.

8. Paying With A Card Still Means Spending Real Money

Children may understand handing a cashier $20 more easily than tapping a phone or inserting a card. At checkout, explain that a debit-card purchase generally takes money from a bank account even though no bills physically change hands. Have your child compare the receipt with the amount you expected to spend and identify where the estimate differed. This creates a natural opening to discuss digital payments, receipts, account balances, and why adults track purchases. It also reinforces an essential principle: convenient payment methods do not make purchases free.

One Grocery Trip Can Build A Lifetime Skill

You do not need a complicated financial curriculum to start teaching children about money. A grocery store already contains budgets, price comparisons, marketing, tradeoffs, digital payments, and dozens of small decisions that mirror adult financial life. The most useful approach is to explain your reasoning and occasionally let children make a low-stakes choice themselves. Repeating these money lessons for kids can gradually turn concepts such as budgeting and value into everyday habits rather than rules they hear only when they are older.

On your next grocery trip, what money decision could you let your child make for themselves, and what might their choice teach both of you? Share your experience and thoughts in the comments.

What to Read Next

Summer EBT Facts That Could Put $120 on Your Grocery Card

SUN Bucks 2026: How Families of Special Needs Students Can Claim Summer EBT Grocery Benefits

The Grocery Costs Parents of Sensory-Sensitive Kids Say No One Talks About

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Personal Finance Tagged With: budgeting, Family Budget, financial literacy, grocery savings, Grocery Shopping, kids and money, Parenting, personal finance, Saving Money, smart shopping

Are Parents Buying Too Many Clothes Before Kids Actually Need Them?

September 23, 2026 | Leave a Comment

Mother Dressing Daughter
Buying children’s clothes months before they are needed can backfire when growth spurts, changing preferences or seasonal timing make those bargains unwearable. Buying fewer future-size pieces and filling wardrobe gaps as they appear can help families avoid wasted spending. (Pexels).

Buying the next size up can feel like smart parenting, especially when a clearance rack makes next season’s clothes look too cheap to pass up. But children do not always grow on a predictable schedule, and that bargain winter coat or stack of jeans may be the wrong size when the weather finally changes. For families trying to control a clothing budget, buying too far ahead can quietly turn savings into wasted money. The problem becomes especially relevant as clothing remains a significant part of back-to-school spending. A better strategy may be buying fewer items now and keeping more money available for what children actually need later.

Families Are Already Spending Hundreds On Clothes

The latest National Retail Federation back-to-school survey found that families with children in kindergarten through 12th grade planned to spend an average of $863.86 on back-to-school purchases in 2026. Of that amount, $250.29 was earmarked specifically for clothing and accessories, while another $174.01 was expected to go toward shoes. Those numbers help explain why seemingly small purchases can quickly strain a kids clothing budget, particularly in households with multiple children. Interestingly, 47% of shoppers said they planned to buy only the essentials for the beginning of school and replenish supplies as needed. That approach can work for clothing too, because waiting provides parents with better information about fit, weather, school activities and what their child will actually wear.

Growth Does Not Follow Your Shopping Calendar

One overlooked risk of stockpiling clothes is that children grow at different rates rather than neatly moving into a new size every six months. The American Academy of Pediatrics’ HealthyChildren.org explains that children tend to grow in spurts, with some growing as much as three times faster during certain seasons than during slower periods. That means buying size 8 shorts nine months early because they are 60% off does not guarantee they will fit when summer arrives. Shoes can be even trickier because an uncomfortable or undersized pair cannot simply be rolled at the cuffs like pants. Parents protecting a clothing budget may therefore be better off keeping only a small reserve of basics in the next size rather than building an entire future wardrobe.

A Sale Is Only A Deal If It Gets Worn

Imagine a parent finds four shirts for $8 each, two pairs of pants for $15 each and a $30 jacket during an end-of-season sale, spending $92 on clothes for next year. If the child skips that size, dislikes half the shirts or needs a different jacket by then, even $40 of unused merchandise wipes out much of the expected savings. This matters because NRF’s 2026 research on back-to-school prices found that 78% of shoppers expected higher prices on back-to-school merchandise, which can make buying early feel especially tempting. Instead of asking only, “How much am I saving today?” parents can ask, “How certain am I that my child will wear this?” That simple question shifts a clothing budget away from chasing discounts and toward calculating the actual value of each purchase.

Secondhand Clothing Changes The Math

Waiting does not necessarily mean paying full retail price later, especially as resale becomes a mainstream alternative to buying new clothes. ThredUp’s 2026 Resale Report, based partly on a survey of 3,268 U.S. consumers, projects the global secondhand apparel market will reach $393 billion by 2030 and says the U.S. secondhand market grew nearly four times faster than the broader retail clothing market in 2025. Research published in Sustainability on secondhand school uniforms also found affordability was the leading motivation for choosing used uniforms among surveyed parents, although availability, sizing and quality remained barriers. Families can check consignment stores, resale platforms, school uniform exchanges and neighborhood groups when an actual need appears instead of buying every future size in advance. Hand-me-downs can stretch a clothing budget even further, particularly for coats, special-occasion outfits and other pieces children may wear relatively few times.

Buy For The Child You Have Today

Buying ahead is not automatically wasteful, especially for predictable necessities such as socks, pajamas or a favorite brand whose sizing a parent already understands. The bigger financial risk comes from confusing a low price with guaranteed savings and filling closets with clothes based on guesses about future growth, weather and preferences. A practical compromise is to keep a limited number of next-size basics, review children’s wardrobes every few months and postpone specialized or expensive purchases until they are genuinely needed. That approach leaves room in the household budget for an unexpected growth spurt without forcing parents to ignore worthwhile sales altogether.

Do you buy your children’s clothes months ahead to catch sales, or have you learned that waiting saves more money in the long run? What strategies help you avoid buying clothes your kids never wear? Share your experiences and money-saving tips in the comments below.

What to Read Next

Here Are the Best Online Shopping Sites for Affordable Kids Clothes

Money-Saving Hacks for Parents Shopping Clearance Clothes After the Holidays

Clothes From Shein and Temu Could Be Hazardous To Your Child’s Health

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Back To School Shopping, children, clothing, Family Budget, family finances, kids clothing, Parenting, Saving Money, secondhand clothing, smart shopping

7 “Cheap” Kids’ Activities That Can Become Surprisingly Expensive

September 21, 2026 | Leave a Comment

Kids Playing Basketball
Activities that look inexpensive at signup can become costly once families add equipment, supplies, travel, costumes, and recurring fees. Asking for the full annual cost upfront can help parents avoid budget surprises. (Pexels).

Parents are always looking for cheap kids’ activities that keep children busy without wrecking the household budget. The problem is that an activity advertised as free, inexpensive, or just a few dollars can carry costs that do not appear until later. Equipment, uniforms, transportation, supplies, tickets, and upgrades can transform an affordable pastime into a recurring expense. A $20 registration fee matters less than what a family ultimately spends over six or nine months. Before signing up, parents should calculate the full-season cost rather than focusing only on the advertised price.

1. Recreational Sports Can Become A Four-Figure Commitment

A neighborhood soccer or basketball league may look inexpensive until equipment, uniforms, tournaments, camps, and travel enter the picture. The Aspen Institute’s Project Play research found that families spent an average of $1,016 on a child’s primary sport in 2024, up 46% from 2019. Spending on that child’s additional sports averaged another $475, pushing total annual spending close to $1,500. A $125 league registration can therefore be a poor estimate of what the season will actually cost. Ask coaches about required equipment, tournaments, travel, private instruction, and future team fees before registering.

2. Dance Lessons Have Costs Beyond Tuition

Dance is another classic example of activities becoming more expensive as children progress. One real-world example comes from Generation Dance Company’s 2025–2026 pricing, where one weekly class costs $50 per month during its nine-month season. However, the studio also lists a $70 costume fee per class and recital tickets costing roughly $17 to $20 each. Add dance shoes, tights, leotards, photos, and transportation, and a family can easily spend hundreds beyond the advertised tuition. Parents should request an all-in estimate that includes costumes and performances before committing to a season.

3. Music Lessons May Lead To An Instrument Upgrade

Learning guitar, piano, or drums can start simply, especially when a child borrows or rents an instrument. But ongoing instruction can quickly become the biggest expense, with School of Rock Arlington listing 30-minute lessons at $220 per month. A child who sticks with music may eventually need a better instrument, replacement strings, reeds, books, accessories, repairs, or performance fees. At $220 monthly, nine months of lessons alone would total $1,980 before buying any equipment. Before purchasing an expensive instrument, ask whether rentals, used equipment, group lessons, or shorter trial programs are available.

4. “Free” Craft Projects Still Require Supplies

Crafting sounds like one of the safest cheap activities because families can often find free tutorials and classes. Yet free instruction does not necessarily mean free participation, particularly when every project requires another set of materials. For example, a Michaels Kids Club class is listed as free online, but the page lists seven suggested supply items totaling $66.93. Families who already own beads, glue, pipe cleaners, and other materials would spend much less, which makes checking the supply list important. Build a reusable craft box, substitute materials already at home, and avoid treating every project as a shopping trip.

5. Summer Day Camp Adds Up By The Week

A reasonably priced day camp can sound like a bargain when compared with overnight camp or full-time child care. According to Care.com’s updated 2026 camp cost guide, average U.S. day-camp fees run approximately $73 to $87 per day, based on American Camp Association figures. At $80 per day, five days cost $400, while six weeks would reach $2,400 before transportation, extended care, lunches, or activity fees. That makes camp one of those cheap kids’ activities where the length of participation matters as much as the daily price. Compare weekly rates, sibling discounts, financial aid, cancellation policies, and before or after-care charges before reserving multiple weeks.

6. Zoo Trips Can Encourage Extra Spending

A zoo outing may begin with admission, but food, souvenirs, parking, special attractions, and repeat visits can change the math. The Houston Zoo’s current membership page lists its family membership at $239 per year for two adults and up to three children and says membership can pay for itself in as few as two visits. That does not automatically make a membership worthwhile because separately ticketed events and discretionary purchases may still cost extra. Families should compare the membership price with what they realistically expect to spend on individual visits rather than assuming unlimited admission guarantees savings. Bringing permitted essentials and setting a souvenir budget can also prevent a modest outing from becoming an expensive day.

7. Scouting Can Carry Costs Beyond Registration

Scouting can provide outdoor activities, skill-building, and social experiences for what initially appears to be a manageable enrollment fee. However, local dues, uniforms, camping gear, trips, and activity charges can raise the actual annual cost. One Houston-area Scouting America Cub Scout pack listing currently shows a $91 cost to join plus $100 in unit dues, while noting that fundraising helps cover expenses. That means the listed starting cost is already $191 before considering camping equipment or other activities. Ask specifically what families typically spend during an entire year and whether used uniforms, shared gear, scholarships, or fundraising credits are available.

The Cheapest Price Is Not Always The Real Price

The common thread behind these activities is that the headline price rarely tells the whole financial story. Parents can protect their budgets by asking for a written list of mandatory and optional expenses before their child becomes committed to an activity. For example, three activities that appear to cost $50 each could eventually consume $1,000 or more once equipment, performances, transportation, and recurring fees accumulate. Setting an annual activities budget also makes it easier to decide which extras genuinely add value for the child.

Which supposedly inexpensive kids’ activity has surprised you most with hidden costs, and what would you warn other parents about? Share your experience in the comments.

What to Read Next

Youth Sports Cost Families $1,016 a Year on Average — 8 Expenses New Parents Don’t Expect

The New Pay-to-Play Rules in Youth Sports That Are Ruining the Game

8 After-School Activities That Can Cost Far More Than Parents Expect

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: cheap kids activities, dance lessons, Family Budget, family finances, kids activities, Parenting, Saving Money, Summer Camp, youth sports

8 Things Parents Often Pay for That Kids Barely Notice

September 19, 2026 | Leave a Comment

Kids Playing Soccer
From child care and school supplies to activities, technology, and teen insurance, many of the biggest parenting expenses happen quietly in the background. Tracking these hidden costs can help families find meaningful savings without sacrificing what their children value most. (Pexels).

Kids notice the new sneakers, birthday presents, and pizza night, but many of the biggest expenses of raising them are practically invisible. Hidden parenting costs can quietly consume hundreds or even thousands of dollars each year without creating a memorable moment for a child. In 2026, families are still navigating expensive child care, school expenses, activities, technology, and insurance. Looking closely at these overlooked bills can help parents decide which expenses are essential and which deserve another look.

1. Child Care That Makes The Workday Possible

Reliable child care may be indispensable to parents, but to children, it is simply part of the weekly routine. According to Care.com’s 2026 Cost of Care Report, average posted daycare costs reached $332 per week for an infant, while nanny care averaged $870. At $332 weekly for 50 weeks, daycare alone could cost a family roughly $16,600 a year. That makes child care one of the largest hidden parenting costs, even though a young child has little understanding of the bill. Parents should compare centers, dependent-care benefits offered through work, sibling discounts, and flexible schedules before assuming their current arrangement is the only practical option.

2. The Never-Ending Stream Of School Purchases

Backpacks and notebooks may seem inexpensive individually, but school-related purchases pile up surprisingly fast. Deloitte’s 2026 Back-to-School Survey found parents expected to spend an average of $557 per K-12 student, with the overall market reaching an estimated $30.4 billion. Children may notice their new backpack but probably not the printer ink, replacement lunch containers, classroom contributions, and second round of supplies purchased later. One smart strategy is waiting until teachers provide confirmed supply lists before buying extras. Parents can also reuse durable supplies and compare unit prices instead of automatically purchasing convenient multipacks.

3. Activities Cost More Than The Registration Fee

Soccer, dance, music, and other activities frequently come with expenses beyond the advertised enrollment price. A LendingTree survey of parents found families with children participating in extracurricular activities spent an average of $731 per child annually, while 62% reported being stressed about paying for them. Uniforms, instruments, equipment, tournament fees, photographs, travel, and meals can push the real price substantially higher. Before registering, ask the organizer for the expected all-in seasonal cost rather than focusing solely on the initial fee. Used equipment, community programs, carpools, and limiting children to one major paid activity at a time can control these hidden parenting costs.

4. Phones And Tablets Become Household Expenses

A device that feels like entertainment to a child can become another recurring household expense for parents. Common Sense Media’s 2025 Census found 40% of children had a tablet by age 2, while nearly one in four had their own cellphone by age 8. The purchase price is only the beginning when families add cellular service, cases, repairs, apps, cloud storage, and subscriptions. Before upgrading, parents should ask whether a cheaper device, prepaid plan, or hand-me-down phone accomplishes the same purpose. Reviewing app-store and streaming charges every few months can also uncover subscriptions children have stopped using.

5. Summer Break Can Create A Second Child-Care Budget

For working parents, summer vacation can replace school with camps, programs, and additional supervision. A 2025 LendingTree survey on summer expenses found parents needing summer child care spent nearly $900 per child on activities and care, and 66% struggled to afford it. Kids may remember swimming or crafts without realizing their parents rearranged an entire monthly budget to make those experiences possible. Families can save by comparing recreation-center programs, sibling discounts, camp bundles, and alternating paid programs with family care when available. Planning months ahead also reduces the risk of being left with only expensive last-minute options.

6. Teen Driving Changes More Than The Gas Bill

Once teenagers start driving, fuel may actually be one of the more obvious expenses. Bankrate’s teen-driver analysis estimates average full-coverage premiums for a household with two adults, one vehicle, and a 16-year-old at $5,936 with a male teen or $5,545 with a female teen, although actual quotes vary considerably. Insurance is therefore one of the hidden parenting costs worth researching before handing over the keys. Parents should request quotes for adding a teen, ask about good-student or driver-training discounts, and compare several insurers. Buying a teenager an inexpensive car does not automatically guarantee inexpensive insurance, so checking premiums before buying the vehicle matters.

7. Convenience Spending Can Become A Habit

Some expenses exist mainly because family schedules leave parents short on time. Delivery fees, takeout after practice, convenience-store snacks, rushed school purchases, and forgotten-item replacements can quietly become recurring expenses. Spending just $25 extra each week because of schedule-driven convenience adds up to $1,300 annually. Parents do not need to eliminate every convenience, but identifying the expensive patterns can make a meaningful difference. Keeping snacks in the car, planning several quick dinners, and creating a school-night checklist can reduce spending without making children feel deprived.

8. Financial Support Does Not Always End At 18

Hidden parenting costs can continue long after children graduate from high school. Bankrate’s Financial Independence Survey found 61% of parents with adult children had sacrificed financially to provide assistance, including delaying other financial priorities. Housing, insurance, phone plans, groceries, tuition, and emergency expenses can blur the line between temporary help and permanent support. Parents should decide what they can comfortably contribute without raiding emergency savings or undermining retirement plans. Clear dollar limits and timelines can support an adult child while gradually shifting financial responsibility to them.

The Expenses Kids Never See Still Count

Children do not need to understand every household bill, but parents benefit from knowing exactly where their money goes. The biggest lesson about hidden parenting costs is that recurring, low-visibility expenses can matter as much as obvious purchases and gifts. A family that cuts just $150 a month from unused subscriptions, convenience purchases, excessive activity costs, or other overlooked spending frees up $1,800 a year. Reviewing these expenses once or twice annually can reveal savings without taking away the things children genuinely value.

Which expense of raising kids surprised you the most, and where have you found clever ways to save money? Share your experience in the comments.

What to Read Next

7 Kids’ Birthday Party Expenses That Have Gotten Completely Out of Hand

5 Medical Expenses Families of Neurodivergent Kids Say They Never Budgeted For

5 Expenses That Parents Need to Abandon For The Sake of Their Kids

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Back to School, child care, Family Budget, family finances, hidden parenting costs, Parenting, raising kids, Saving Money

Your Child’s Social Life May Be One of the Most Expensive Parts of Parenting

September 18, 2026 | Leave a Comment

Teens At The Mall
Birthday parties, extracurricular activities, gifts, meals and transportation can turn a child’s busy social calendar into a four-figure annual expense. Setting a dedicated social budget can help families protect both friendships and household finances. (Pexels).

Your child’s social calendar may look harmless one event at a time: a birthday party Saturday, soccer practice Tuesday, a movie with friends Friday. But add registration fees, gifts, uniforms, restaurant meals, rides, clothes and last-minute spending, and the cost of kids’ social activities can quietly become a serious household expense. Unlike rent or groceries, these costs are unpredictable, which makes them particularly difficult to budget for. Parents may also feel pressure to say yes because turning down an invitation can feel like limiting a child’s friendships. The challenge is finding a way to support a healthy social life without allowing social spending to control the family budget.

Social Spending Is Bigger Than It Looks

The cost of kids’ social activities extends far beyond admission prices and activity fees. Deloitte’s 2025 Back-to-School Survey found that 90% of surveyed parents planned to enroll their children in extracurricular activities, with average planned spending of $532 per child on fees and equipment. Meanwhile, an April 2026 LendingTree survey found that 55% of parents with children under 18 spend at least $1,000 per month on child-related expenses overall, while 82% said raising children had become more expensive during the previous year. Extracurriculars alone were named the biggest financial strain by 9% of respondents, behind education savings and food. Those figures help explain why expenses that individually seem manageable can become painful when they repeatedly hit the same monthly budget.

The Hidden Costs Can Hurt Most

A $150 sports registration fee rarely tells parents what a season will actually cost because equipment, uniforms, tournament travel, meals and team events can follow. The same applies to dance, theater, clubs, and birthday parties, where photos, costumes, gifts or transportation may effectively become part of the price of participation. Consider a family spending $532 on one child’s extracurriculars, plus eight $30 birthday gifts, four $25 social outings and $300 for extra clothing, transportation and meals: that is $1,172 before an expensive trip or summer program appears. The pressure is real, as a 2024 LendingTree parenting survey found that 45% of parents overall had felt a need to overspend on their children to keep up with other parents or peers. A useful budgeting question, therefore, is not simply “Can we afford the registration?” but “What will saying yes probably cost us from beginning to end?”

Friendship Has Value But Spending Has Limits

Cutting every social expense is not necessarily the answer because friendships themselves can play an important developmental role. A systematic review published in BMC Public Health examined 43 studies and found that better friendship quality was generally associated with favorable measures including life satisfaction, happiness, self-esteem, and lower loneliness, although much of the evidence was cross-sectional and does not prove causation. That distinction matters because paying for more activities does not automatically create better friendships. Parents can support relationships through inexpensive opportunities such as neighborhood get-togethers, library programs, school clubs, home movie nights and shared outdoor activities. Managing the cost of kids’ social activities should therefore focus on preserving meaningful connections rather than trying to purchase every available social opportunity.

Summer Can Create Another Spending Surge

The school year is not the only time social and activity costs can strain a family budget. A 2025 LendingTree summer survey found parents who required summer child care spent an average of $893 per child on activities and care, while 66% said they struggled to afford those expenses. Nearly half, 48%, said they cut nonessential spending such as dining and entertainment to compensate, while 19% reduced spending on essentials including groceries or utilities. Summer camps can provide child care, friendship and enrichment simultaneously, but families should separate expenses they truly need for work coverage from optional programs driven mainly by social pressure. Asking about sibling discounts, scholarships, early registration rates, community recreation programs, and used equipment can reduce the cost of kids’ social activities without automatically removing the experience.

The Goal Is Connection Not Keeping Up

Parents do not need to choose between financial stability and giving children a meaningful social life. The smarter approach is recognizing the cost of kids’ social activities as a genuine budget category instead of treating every invitation, registration and outing as an isolated surprise. Decide what your family can comfortably spend, talk openly with older children about tradeoffs, and reserve money for the experiences they value most. Children can still build friendships and memorable experiences without attending every party, joining every travel team or matching what another family spends.

Where would you draw the line when supporting your child’s social life starts competing with your family’s financial goals, and have you found a strategy that works? Share your experience in the comments.

What to Read Next

Are Family Photo Days Becoming Another Expensive Parenting Obligation?

Some Parents Are Spending Nearly $1,000 Getting One Child Back to School

The Grandparent Spending Problem: What to Do When They Keep Buying Your Kids Everything

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: children, extracurricular activities, Family Budget, family finances, kids activities, Parenting, parenting costs, Saving Money, social activities

Are Family Photo Days Becoming Another Expensive Parenting Obligation?

September 17, 2026 | Leave a Comment

Photographer Taking Family Photo
</strong> Professional family photo sessions can cost several hundred dollars before parents add outfits, prints, styling, and other extras. Setting a budget before booking can keep a meaningful tradition from becoming a financial obligation. (Pexels).

Family photo day can start with a simple goal: get one good picture of everyone together before the kids grow another six inches. Then comes the photographer deposit. Someone needs a new shirt. Another child needs shoes. Maybe there’s a haircut, holiday cards, prints for grandparents, and the irresistible temptation to buy extra digital images once the gallery arrives.

Suddenly, preserving a family memory has become a several-hundred-dollar event. Professional photography can absolutely be worth the money. But as family portraits become more elaborate—and more visible on social media—parents may want to separate the pictures they genuinely value from another parenting expense they feel obligated to pay.

Family Photography Really Can Cost Several Hundred Dollars

The price isn’t entirely in parents’ imaginations. The Bureau of Labor Statistics reported that prices in its photographers and photo-processing category were 3.8% higher in August 2026 than a year earlier. Actual family-photography prices vary enormously based on location, photographer experience, session length, and what’s included.

For example, one current Raleigh-area photographer lists a one-hour family session at $600. That includes 25 retouched digital files, while a 20-minute mini session costs $400 and includes seven files. Another photographer in the same market charges $375 for a family session lasting up to an hour but includes only five digital images. A 20-minute seasonal mini costs $300 and includes three images.

That illustrates why asking only, “How much is the session?” can give parents the wrong answer.

The $375 Session Might Not Really Cost $375

Imagine booking that $375 session because it fits your budget. You receive the gallery and discover five photographs are included—but you love 15. That photographer currently charges $225 for 15 digital images or $300 for the entire gallery, meaning the final photography bill could be substantially higher depending on what you select.

Other photographers structure packages differently. Some include dozens of files or the complete gallery from the beginning.

Before paying a deposit, ask exactly what you’re getting: session length, number of people allowed, number of edited images, additional-image prices, print costs, travel fees, taxes, and any required minimum purchase. Otherwise, you’re comparing advertised prices rather than actual family-photo costs.

Mini Sessions Can Save Money, But Read the Details

A mini session can be a good compromise for families who mainly want an updated portrait for the wall or holiday card. Current examples show just how different those packages can be.

One Raleigh-area photographer charges $300 for a 20-minute seasonal family mini with three digital images, while another lists a 20-minute mini at $400 with seven retouched digital files. That doesn’t mean either price is unreasonable. It means the word “mini” describes the session format, not necessarily a bargain price.

Ask how many images are included, whether you’ll be able to purchase extras and how much those additional files cost. Also consider your children. Fifteen or 20 minutes may be plenty for older kids who cooperate easily, but paying for a tightly scheduled mini can be frustrating if your toddler needs 15 minutes just to stop hiding behind your leg.

The Photographer May Be Only Half the Photo-Day Budget

Now add the expenses that don’t appear on the photographer’s website. Suppose a family books a $375 session and buys $60 worth of clothing for each parent and two children. The family has already reached $615 before buying a single print. Add $35 for a child’s haircut, $50 for holiday cards, and $40 for framed prints for grandparents, and photo day reaches $740.

That’s an illustrative example rather than a national average, but it’s exactly why families should calculate the entire event instead of looking only at the session fee.

You don’t need new outfits, professional hair and makeup, restaurant reservations afterward or an elaborate coordinated wardrobe to take meaningful family photographs. Building everyone’s outfit around clothing already in the closet can eliminate one of the easiest photo-day expenses.

Social Media Can Make Optional Spending Feel Normal

There’s another reason family photos can start feeling less optional: we see everyone else’s. Research suggests social comparison really can influence how parents perceive expectations.

A 2026 study published in Family Relations involving 909 parents found that upward comparisons with other parents on social media were associated with parental anxiety and overprotective parenting behaviors. That study wasn’t specifically about professional photography, so it doesn’t prove Instagram causes parents to book expensive portrait sessions. But it does provide useful context for a familiar experience: repeatedly seeing polished examples of other families can affect perceptions of what “normal” parenting looks like.

Earlier Pew Research Center research found that 24% of parents who used social media said they at least sometimes felt pressure to post things that made them look like a good parent. A beautiful annual family portrait can be a tradition you love without becoming evidence that you’re doing parenting correctly.

Understand What “Digital Images Included” Actually Means

Parents should also understand what they’re buying when a photographer promises digital files. The U.S. Copyright Office explains that photographers generally own copyright in the original photographs they create from the moment the images are made. Receiving a digital image therefore doesn’t automatically mean you’ve purchased the copyright.

Many family photographers instead provide clients with a personal-use or print release allowing them to download, share, and print selected photographs. For example, several current photographers explicitly include high-resolution digital files and print releases in their family packages.

Before booking, ask whether you receive high-resolution files, whether you can print them yourself, whether social-media sharing is permitted, and whether downloaded images contain watermarks. Those questions are especially important if your main goal is making your own holiday cards or inexpensive prints.

Try a Family Photo Budget Before You Book

Instead of deciding whether professional photography is “too expensive,” decide what family photos are worth to your family. Suppose you set a $400 annual photography budget. You might spend all $400 on one professional session, book a $200 mini and keep the remainder for prints and cards, or skip professional photographs this year and put the money toward a larger milestone session next year. Another option is alternating years.

A family that spends $500 on professional portraits every other year instead of annually reduces the average cost to $250 per year while still documenting how everyone changes over time. That approach can be particularly useful when you’d rather save professional photography for newborn pictures, graduations, milestone birthdays, or extended-family gatherings.

Some of the Best Family Pictures Cost Almost Nothing

Professional photographers bring skill, equipment, editing experience, and an ability to get good photographs from children who seem determined not to cooperate. But they’re not the only people capable of documenting your family. Modern smartphones, inexpensive tripods and camera timers make it possible to take surprisingly good family pictures at home, at a park or during a vacation you’re already taking.

You can also trade photo-taking duties with another family: take their pictures for 10 minutes, then have them take yours. The result may not belong in a professional photography portfolio, but twenty years from now you may care considerably more about who’s in the photograph than whether everyone wore perfectly coordinated shades of beige.

Make Family Photos a Choice, Not Another Parenting Bill

There’s nothing frivolous about paying for professional family photography when you can afford it and genuinely value the results. The problem begins when an optional tradition quietly becomes another annual bill parents believe they’re supposed to pay. Before booking, calculate the all-in cost: photographer, extra images, clothes, grooming, travel, prints, and cards. Then compare that amount with what else the same money could do for your family. Maybe you happily decide the photographs are worth every dollar. Or maybe this is the year you put the phone on a tripod, tell everyone to squeeze together, and accept that one child will probably make a ridiculous face. Either way, your family still gets the memory.

How much would you comfortably spend on family photos, and do you think social media has made professional photo sessions feel more obligatory for parents?

What to Read Next

Why Your Happy Family Photos Can Trigger Envy and Anxiety

Great Family Photos Don’t Have to Be Expensive

8 Ways Kids Can Quietly Blow the Family Budget Once School Starts

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Family Budget, family photo sessions, family photos, holiday photos, parenting costs, parenting expenses, photography costs, Saving Money

September Is a Good Month to Find Out What Your Kid Actually Uses From That Huge School Supply Haul

September 16, 2026 | Leave a Comment

Sharp Pencils
September is a smart time for parents to check backpacks and homework spaces to see which school supplies children actually use. Saving untouched extras for later can reduce unnecessary purchases and make next year’s back-to-school shopping easier. (Pexels).

By September, the excitement of back-to-school shopping has usually been replaced by something much more useful: evidence.

Those carefully chosen notebooks, colorful pens, giant packs of pencils, folders, binders, highlighters, glue sticks, and elaborate organizers have now had several weeks to prove whether your child actually needs them. Some are already being used daily, while others may not have moved from the bottom of a backpack or bedroom desk since the first day of school.

That matters when families are spending hundreds of dollars getting children ready for class. The 2026 Deloitte Back-to-School Survey found that surveyed parents expected to spend an average of $557 per K–12 student, with total back-to-school spending projected at $30.4 billion.

Instead of treating August’s shopping list as final, use September to conduct a simple school supply audit. The goal isn’t to criticize what you bought—it’s to figure out what your child actually uses so you can stop buying duplicates, make smarter restocking decisions and create a much more accurate list next year.

Start With What Has Actually Been Used

The easiest school supply audit begins with your child’s backpack, desk, locker supplies, and homework area.

Look for evidence rather than asking, “Do you need this?” A notebook with 20 pages of classwork is clearly serving a purpose, while an untouched three-ring binder may tell a different story.

Make four quick categories: used constantly, used occasionally, unopened, and already running out.

You may discover that your middle schooler requested five notebooks in August, but two teachers handle nearly everything digitally. On the other hand, an elementary student who started with six glue sticks may already be asking for more.

Pay attention to what’s disappearing fastest. Those are the supplies worth buying when you see a genuinely good sale because you now have evidence that your household will use them.

Compare the Teacher’s List With September Reality

Supply lists are a starting point, not necessarily a prediction of how every classroom will operate for the next nine months.

Teachers can change assignments, classroom routines may become clearer after the first few weeks, and students sometimes discover that an item they thought they’d use every day isn’t particularly useful.

That’s one reason Consumer Reports recommends asking teachers which supplies are needed immediately and purchasing other items later rather than feeling pressured to buy everything before the first day.

September is the perfect time to revisit that idea.

Pull up the original school or teacher supply list and place it next to what’s actually in your child’s backpack. Mark items as essential, occasionally needed, not used yet, or needs replacement soon.

And before declaring something unnecessary, ask your child whether the teacher has mentioned needing it later. Graph paper, index cards, poster board, and specialty notebooks may be intended for projects or units that haven’t started yet.

Find the Supplies You Already Own Before Buying More

September can also expose one of the easiest ways families waste money on school supplies: buying another package because nobody knows where the first one went.

Before restocking anything, check the backpack, child’s bedroom, homework station, kitchen junk drawer, family office and leftover school-supply bins from previous years.

You might be surprised by how much inventory your house already contains.

If your child says they’re running out of pencils but you discover two unopened 24-count boxes in a closet, you’ve found the next 48 pencils for $0 in additional spending. The same principle applies to loose-leaf paper, pens, erasers, glue sticks, index cards and notebooks.

Consumer Reports has also advised families to take inventory of supplies they already own before purchasing more.

Consider creating one designated school-supply bin at home. When something runs low, everyone knows where to look before another item lands on the shopping list.

Put Unused Supplies in a “Wait” Box

Don’t immediately donate or throw away everything that hasn’t been used by September.

Instead, create a box labeled something like “School Supplies — Use Before Buying More.”

Put unopened notebooks, folders, index cards, extra pencils, markers, and other currently unnecessary items there. If a teacher asks for one of those supplies in November, you already own it.

If the items remain untouched at the end of the school year, move them directly into next year’s supply inventory.

This approach also prevents unused supplies from becoming invisible clutter scattered across multiple drawers and closets. A $3 notebook doesn’t seem financially important by itself, but ten or twenty small duplicate purchases across a school year can quietly add to the family’s education budget.

Look at What Broke, Not Just What Was Used

A September audit should also answer another question: Did the cheapest version actually save money?

Suppose you bought a $4 binder that already has a broken ring or a bargain backpack with a failing zipper. Replacing an inexpensive product multiple times can eventually cost more than buying one durable version.

On the other hand, you may discover that the premium organizer, specialty pencil case or expensive mechanical pencils weren’t necessary at all.

That’s why the audit isn’t simply about buying cheaper products. It’s about identifying where paying more improved durability and where paying more added nothing your child actually needed.

That distinction can make next year’s shopping much smarter.

Give Your Child a Role in the Audit

This can also become a simple money lesson instead of another household chore handled entirely by a parent.

Ask your child to sort supplies into three categories: I use this a lot, I sometimes use this, and I haven’t used this yet.

Then ask one more question: “If we were buying school supplies again tomorrow, which of these would you still ask me to buy?”

That question can be surprisingly revealing.

Older children and teenagers can go a step further. Show them what several of those items cost and ask whether they’d spend the same amount again now that they’ve used—or ignored—the products for several weeks.

Keep the conversation neutral. The point isn’t to make a child feel guilty because the $8 planner you bought hasn’t been opened. You’re helping them connect purchasing decisions with actual value, which is a financial skill they’ll eventually need when spending their own money.

Families Are Already Looking Harder for Value

This exercise fits with the way many parents approached the 2026 back-to-school season.

Deloitte found that 31% of surveyed K–12 parents used four or more cost-saving behaviors, while inflation-adjusted planned family spending was down 6% from the previous year. Interestingly, those highly value-conscious parents weren’t necessarily the lowest spenders; Deloitte found they planned to spend about 14% more than other shoppers, suggesting that value shopping can mean spending selectively rather than simply buying the cheapest possible products.

The National Retail Federation similarly reported that families were using discounts, promotions and secondhand products to stretch back-to-school budgets as classes began.

Price pressure was clearly on parents’ minds. Earlier in the season, NRF found that 78% of back-to-school shoppers expected higher prices, and roughly one-third said they typically plan their shopping around summer sales.

That makes September’s audit useful for more than organizing the desk. Knowing exactly which products your child burns through gives you a much better idea of which clearance items or future promotions are actually worth buying.

Turn September Into Your Restocking Baseline

Once you’ve finished the audit, make a short list with three headings:

  • Buy again when needed: Pencils, glue sticks, paper or anything your child is clearly consuming.
  • Already have extras: Items sitting unopened in your supply box.
  • Don’t automatically buy next year: Products that sounded essential in August but aren’t being used.

Save that list somewhere you’ll actually find it next summer—your phone’s notes app, family budgeting spreadsheet or calendar reminder works better than a piece of paper destined for a drawer.

You can even record quantities. If your child goes through roughly one glue stick every three weeks but uses only one notebook all semester, next August’s shopping list becomes much easier to estimate.

September Can Make Next August Cheaper

The biggest advantage of a September school supply audit isn’t necessarily what you save this month. It’s the information you carry into the rest of the school year and eventually into next summer.

Before the school year started, you were shopping largely from a list and making educated guesses about what your child would use. Now you have several weeks of real-world evidence.

Use it to restock genuine essentials, keep useful extras organized, skip unnecessary duplicates and recognize when paying a little more for durability might actually save money.

With surveyed parents expecting to spend $557 per K–12 student this year, even trimming a few unnecessary purchases matters. More importantly, you’re replacing the annual habit of “buy everything just in case” with a much simpler rule: buy based on what your child actually uses.

What school supply did you buy this year that your child has barely touched—and will it change what you put in the cart next August? Share your experience in the comments.

What to Read Next

Sensory-Friendly School Supplies: What Helps and What Can Be Skipped

10 Places Parents Can Find Free School Supplies Before Classes Begin

Teachers Beg Parents: Stop Buying These 7 Expensive School Supplies

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Back to School, education, Family Budget, household budgeting, Kids, Parenting, Saving Money, school shopping, school supplies, September

Some Parents Are Quietly Saying No to Expensive Birthday Parties

September 14, 2026 | Leave a Comment

Kids Birthday Party
More parents are reconsidering costly venues, elaborate decorations, and party extras as they look for meaningful ways to celebrate children without straining the family budget. Research suggests games, friends, food, and shared experiences can matter more than expensive décor. (Pexels).

A child’s birthday can start with a seemingly simple plan—pizza, cake and a few friends—and somehow end with a venue deposit, balloon arch, custom cookies, party favors, matching decorations and a credit-card charge that looks more like a weekend getaway. Some parents are beginning to question whether all of that spending actually makes the birthday better.

A 2024 What to Expect survey of 404 women found parents spent an average of $314 on a child’s birthday party, while 20% reported spending more than $500. One parent surveyed had spent $7,000 on a party complete with catering, entertainment and a professional photographer. There’s nothing wrong with an elaborate celebration when a family genuinely wants one and can comfortably afford it. But parents looking for affordable birthday parties have another option: decide what their child will actually enjoy first, set a spending limit and stop paying for extras that mostly exist to make the party look impressive.

Birthday Parties Have Plenty of Places to Overspend

The problem isn’t usually one outrageous expense. It’s the accumulation of $20, $40 and $75 upgrades. A venue might start with a $250 package, but then come extra guests, food upgrades, decorations, party favors and additional activity time. A home party eliminates the venue charge but can introduce its own shopping list: balloons, tablecloths, plates, themed decorations, food, drinks, cake, craft supplies and goodie bags.

The What to Expect survey found the average party cost increased with children’s ages. Parents reported spending about $279 on parties for children ages 1–2 compared with $344 for children ages 6–9. That makes a birthday budget worth establishing before opening Pinterest, browsing party venues or asking a child to choose from unlimited possibilities.

Social Media Can Quietly Raise the Standard

Parents today aren’t comparing their child’s birthday only with the parties they attended as kids. A few minutes scrolling through social media can produce professionally styled balloon installations, elaborate dessert tables, personalized signs, bounce houses, character performers and party favors that look ready for a photo shoot.

Before adding an upgrade, try asking a simple question: Would my child notice if this wasn’t there?

The answer may save quite a bit of money.

Kids May Care More About What They Do Than How the Party Looks

Some 2026 research offers parents another reason to reconsider where the party money goes. In a Chuck E. Cheese-sponsored international survey of 4,985 parents of children ages 2–12, 34% said more games and activities would have most improved their child’s previous birthday party. Only 23% chose a special theme or decorations.

The company’s broader birthday research also found gifts, family time and birthday cake were nearly tied among the highlights parents associated with children’s birthdays. That doesn’t prove children never appreciate an elaborate theme, and another Chuck E. Cheese study actually found many children prefer elaborate celebrations. The more useful takeaway is that expensive-looking isn’t necessarily the same thing as fun.

If your child would rather have six friends running through a backyard scavenger hunt than pose in front of a $300 balloon display, put the money into the scavenger hunt.

Try a $150 Birthday Party Before Assuming You Need $500

A lower-cost party doesn’t have to feel like a financial compromise.

Imagine giving yourself a $150 ceiling and letting your child help decide how to use it:

  • Pizza and drinks: $45
  • Grocery-store cake or cupcakes: $25
  • Decorations and paper goods: $20
  • Backyard games, crafts or activity supplies: $35
  • Small favors or take-home treats: $15
  • Extra cushion: $10

Total: $150

The exact prices will vary, but the exercise matters more than the numbers. Starting with a limit forces the family to decide what gets priority instead of continuing to add purchases until the party is over. Holding the celebration at home or a free local park, sending digital invitations and scheduling the party between traditional meal times can potentially reduce costs further.

Give the Birthday Child a Choice Between Experiences

Older children can participate in the budgeting decision without making them feel responsible for the family’s finances.

Suppose you’ve decided you’re comfortable spending $250. Instead of asking, “What do you want for your party?” offer two or three options that already fit the budget.

For example:

Option A: Eight friends come over for pizza, cake, games and a movie.

Option B: Your child chooses three friends for a more expensive activity such as bowling, skating or another local attraction.

Option C: Have a simple family celebration and put part of the birthday budget toward one larger gift or experience.

Now the conversation isn’t about what the family “can’t afford.” It’s about choosing which option provides the most value.

That’s also a useful introduction to a financial lesson children will encounter throughout life: choosing one thing frequently means giving up something else.

Don’t Forget the Cost of Attending Everyone Else’s Parties

Birthday-party inflation doesn’t only affect the family hosting the celebration. Parents with school-age children may receive invitations throughout the year, each potentially requiring a gift, card, transportation and sometimes additional spending. That’s one reason “no gifts” parties have attracted interest. In the same What to Expect research, 13% of parents said they were asking guests not to bring presents, while about half said they didn’t want gifts or didn’t particularly care whether their children received them.

A no-gift request can reduce clutter for the birthday family while also removing financial pressure from invited families. Another option is simply keeping gifts modest. A child’s friendship doesn’t need to be measured by the price of the present brought through the door.

Decide Which Birthday Traditions Are Actually Worth Paying For

There is no financial rule saying a $500 birthday party is irresponsible—or that a $75 backyard celebration is automatically better. A family with plenty of room in its budget may genuinely love planning a large party. Another household may decide the same $500 would be better spent on a family day trip, summer camp, sports fees, savings or simply keeping the monthly credit-card balance lower. The mistake is letting someone else’s party establish your family’s spending standard.

Pick two or three things your child genuinely cares about. Set the budget before shopping. Spend freely on the priorities that fit inside that number and feel comfortable skipping everything else. Years later, the detail your child remembers may not be whether the balloons matched the napkins. It may simply be that their favorite people showed up, they got to choose the cake, and everyone had fun.

Would you rather spend $500 on one large birthday party or give your child a smaller celebration and use the difference for something else?

Saving Money on Kids Birthday Parties

7 Kids’ Birthday Party Expenses That Have Gotten Completely Out of Hand

The $500 Birthday Party Question: When Did Kids’ Birthdays Get So Expensive?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: affordable birthday parties, birthday parties, Family Budget, family finances, Kids, Parenting, party planning, Saving Money

Is $20 Still Enough for the Tooth Fairy?

September 13, 2026 | Leave a Comment

Stack Of 20 Dollar Bills
</strong> The average Tooth Fairy payout rose to $5.84 per tooth in 2026, making a $20 surprise far more generous than the national average. Families can keep the tradition magical without feeling pressured to compete with bigger payouts. (Pexels).

Twenty dollars under a pillow might not buy what it once did at the grocery store, but there’s at least one place where it’s still a small fortune: the Tooth Fairy market. The average payout for a lost tooth rose 17% in 2026, according to the latest national survey, but parents are still leaving nowhere near $20 for the typical tooth. In fact, a $20 bill is more than three times the current national average. That’s good news for parents who hear that a classmate’s Tooth Fairy supposedly leaves $20, $50, or some other eye-popping amount. Before adjusting your household’s going rate for inflation—or playground peer pressure—here’s what parents are actually paying and how quickly a seemingly small tradition can add up.

The Going Rate for a Tooth Is Now $5.84

The Delta Dental 2026 Original Tooth Fairy Poll found that the average value of a lost tooth increased from $5.01 in 2025 to $5.84 in 2026, a 17% jump. That ended two consecutive years of declining Tooth Fairy payouts. The survey was conducted among 1,000 parents of children ages 6 to 12, so $5.84 shouldn’t be interpreted as a rule families are expected to follow. Plenty of Tooth Fairies presumably leave $1, $5, $10, gifts, or whatever makes sense for the household. But the national figure provides a useful answer to the original question: $20 is still extremely generous. It’s roughly 3.4 times the current average payout for one lost tooth.

The First Tooth Apparently Deserves a Bonus

Not every tooth is worth the same amount in the Tooth Fairy economy. Delta Dental found that the average first tooth payout reached $7.17 in 2026, up from $6.24 last year and about 23% higher than the average ordinary tooth. More than one-third of parents—38%—said their Tooth Fairy leaves extra for the first tooth compared with later ones. That gives parents who like the idea of a $20 surprise an easy compromise. Instead of establishing $20 as the going rate for every tooth, make the first one a milestone: $20 for tooth No. 1 and a smaller, sustainable amount for the rest. The child still gets the thrill of discovering a $20 bill under the pillow without accidentally negotiating a $400 childhood dental contract.

Twenty Dollars a Tooth Eventually Becomes $400

Children typically lose 20 primary, or baby, teeth as their permanent teeth come in. At $20 each, that works out to: $20 × 20 teeth = $400 per child. For three children, the eventual Tooth Fairy obligation could theoretically reach $1,200.

Of course, nobody is funding all 20 teeth on the same Tuesday night, and $20 every few months may fit comfortably into some household budgets. The more useful question is whether parents want to establish an amount they’re willing to repeat when the next tooth starts wiggling. By comparison, paying the current $5.84 national average for 20 teeth would total about $116.80 per child. And there’s no requirement to hit that average, either.

Your Zip Code May Affect the Tooth Fairy’s Wallet

Like housing, groceries, and gasoline, Tooth Fairy prices apparently vary depending on where you live. Delta Dental found the Northeast had the country’s highest average payout in 2026 at $6.45 per tooth, followed by the West at $5.99 and the South at $5.89. The Midwest had the lowest average at $5.27. Even there, however, Tooth Fairy generosity jumped dramatically: the Midwest’s average rose 52% from the previous year. The Northeast climbed 41%. Those regional differences are another reason not to worry too much about what another parent says is the “normal” amount. There isn’t one universally accepted Tooth Fairy rate—and even the national average changes substantially from year to year.

Tooth Fairy Inflation Has Been Remarkable

Parents who remember finding a dollar under their own pillows aren’t imagining how dramatically things have changed. Delta Dental began tracking Tooth Fairy payouts in 1998, when the average lost tooth brought just $1.30. By 2026, that had reached $5.84—an increase of 349%.

Interestingly, Delta Dental has historically compared its Tooth Fairy Index with movements in the S&P 500. The relationship hasn’t always held, but in the latest survey period the average tooth payout increased 17% while the S&P 500 rose about 16%. Parents probably shouldn’t start valuing incisors according to their investment portfolios, but it’s a fun illustration of just how much this tiny childhood transaction has changed over the past 28 years.

Cash Isn’t the Only Thing Appearing Under Pillows

Parents who don’t want to keep raising the cash payout have plenty of company. Delta Dental found that 32% of children received a physical gift from the Tooth Fairy in 2026, up substantially from 19% in 2025. That opens up inexpensive possibilities: a small book, unusual coin, craft, handwritten note, certificate, sticker, or another little surprise.

Greenlight suggests personalized Tooth Fairy notes, miniature letters and certificates as ways to make the experience memorable with or without cash. And the experience itself seems to matter. Half of parents in Delta Dental’s survey said Tooth Fairy visits give their children something to be excited about, while 42% said the tradition makes their child feel special and 39% said it creates a memorable bonding moment. A $2 bill accompanied by a tiny handwritten letter might therefore generate more excitement than parents expect.

That $5 Can Become a Child’s First Money Lesson

Tooth Fairy money can also be some of the first cash a child considers truly their own. The National Foundation for Credit Counseling recommends using the tradition to introduce basic concepts including recognizing currency, spending, saving, and setting goals. You don’t have to turn a magical childhood tradition into a personal-finance seminar before breakfast.

If the Tooth Fairy leaves $5, simply ask what the child wants to do with it. They might spend part, save part toward a toy, or combine several future Tooth Fairy visits to reach a larger goal. For younger children, even learning that one $5 bill is worth more than several smaller coins can be a useful introduction to how money works.

Don’t Let the Playground Set Your Tooth Fairy Budget

Eventually, many children discover that Tooth Fairies apparently operate under wildly different compensation packages. One friend gets $2. Another gets $10. Someone inevitably claims to have received $50. Parents don’t have to compete with any of them. Choose an amount that fits your budget and a tradition you’re comfortable repeating. Maybe that’s $5 for each tooth, $10 for the first one, an occasional special gift, or a shiny dollar coin and handwritten note.

And if your Tooth Fairy leaves $20? The latest numbers suggest your child is doing extremely well in the lost-tooth market.

How much does the Tooth Fairy leave at your house—and have your kids ever complained that a friend’s Tooth Fairy pays better? Share your going rate in the comments.

What to Read Next

12 Heart-Melting Things Kids Do That We Never Want to Forget

8 Awkward Milestones That No One Warns Parents About

7 Childhood Milestones That Come With Surprise Costs

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: Family Budget, family finances, financial literacy, kids and money, Parenting, Saving Money, Tooth Fairy, Tooth Fairy payout

7 Kids’ Birthday Party Expenses That Have Gotten Completely Out of Hand

September 13, 2026 | Leave a Comment

Birthday Party
From elaborate venues and custom cakes to balloon displays and overflowing goodie bags, children’s birthday celebrations can quickly cost hundreds of dollars. Setting a budget before choosing extras can keep the focus on fun instead of financial pressure. (Pexels).

A child’s birthday used to mean cake, balloons, pizza, and a handful of friends running around the backyard, but today, some celebrations look more like professionally produced events. Parents can easily encounter hundreds of dollars in venue fees before adding food, decorations, entertainment, and favors, while some elaborate parties climb past $1,000. Care.com notes that popular activity-space parties can run roughly $250 to $500 before every extra is included. As kids’ birthday party costs rise, families may be wondering which expenses are actually making the day better and which ones have simply gotten out of hand.

1. Elaborate Party Venues

Indoor playgrounds, trampoline parks, sports facilities, and specialty venues make parties convenient, but that convenience can carry a serious price tag. Current listings show how quickly kids’ birthday party costs can escalate, with some facility packages starting around $500 and larger private events reaching $850 or more. The package may cover activities and basic supplies, yet food, extra guests, upgraded rooms, and longer party times can push the bill higher. A family inviting 20 children could therefore spend several hundred dollars before buying the birthday cake. Parents should compare the complete price, including required deposits and add-ons, rather than focusing only on the advertised starting rate.

2. Professional-Level Decorations

A few balloons and a colorful tablecloth apparently are no longer enough for some parties, especially when social media is providing endless inspiration. Balloon arches, personalized backdrops, elaborate centerpieces, themed signs, and professionally styled dessert tables can transform an ordinary room into a miniature event venue. The problem is that children may spend five minutes admiring decorations before racing off to play with their friends. Parents can recreate much of the atmosphere by choosing two or three high-impact decorations and skipping the coordinated extras. When controlling kids’ birthday party costs, decorations are one of the easiest categories to scale back without reducing the fun.

3. Over-The-Top Birthday Cakes

The humble sheet cake now competes with towering custom creations featuring fondant characters, intricate designs, and multiple tiers. Specialty cakes can become particularly expensive when parents request extensive customization, while cupcakes, cookies, and other desserts add another layer to the food budget. Food prices remain substantially higher than they were before the pandemic, with NerdWallet reporting that food prices were about 34.6% above 2019 levels as of 2026. A supermarket cake, homemade dessert, or smaller custom cake paired with inexpensive cupcakes can still create a memorable candle-blowing moment. Unless elaborate cake design is especially meaningful to your child, spending heavily on something that disappears within minutes deserves reconsideration.

4. Entertainment That Rivals A Festival

Magicians and face painters have been joined by character performers, mobile petting zoos, elaborate inflatables, gaming trucks, and other premium entertainment options. One activity can be manageable, but stacking multiple attractions quickly turns a two-hour children’s gathering into an expensive production. Parents may feel pressure to provide constant entertainment, even though younger guests are often perfectly happy with music, playground equipment, crafts, or a scavenger hunt. Care.com recommends inexpensive alternatives such as simple games and activities that can double as party favors. Picking one standout activity instead of several can dramatically reduce kids’ birthday party costs while still giving children something exciting to remember.

5. Goodie Bags Packed With Gifts

Party favors were once a few pieces of candy and a tiny toy, but some goodie bags now resemble full birthday presents. Personalized cups, toys, craft kits, accessories, and themed merchandise multiplied by 15 or 20 guests can quietly become a major expense. There is also the practical problem of parents taking home another collection of inexpensive plastic items their children may quickly forget. Consider one useful item, a take-home craft, or treats collected from a piñata instead of assembling elaborate gift bags. Guests came to celebrate the birthday child, and hosts should not feel obligated to send everyone home with a substantial present.

6. Food For An Oversized Guest List

The guest list can turn an affordable party into an expensive one faster than almost anything else. Inviting an entire class may mean feeding 20 or 30 children, plus siblings and parents who remain during the celebration. Restaurant and catered food costs can multiply quickly, particularly when hosts add adult meals, drinks, snacks, and desserts. Scheduling a party between traditional meal times can reduce expectations for a full lunch or dinner while still allowing you to serve cake and light snacks. A smaller guest list also gives the birthday child more time to interact with the friends they genuinely wanted there.

7. Personalized Everything

Custom invitations, banners, shirts, water bottles, napkins, labels, cake toppers, and favor bags can make a birthday theme look impressively coordinated. Unfortunately, personalization can also turn inexpensive party supplies into premium purchases that are useful for only a few hours. Digital invitations are a particularly easy place to save because families can avoid printing and postage while making RSVPs easier to manage. Parents.com also recommends digital invitations and shopping strategically rather than paying party-store markups when planning celebrations on a budget. Cutting unnecessary customization helps control kids’ birthday party costs without making the celebration feel generic or thoughtless.

Memories Matter More Than The Party Price Tag

There is nothing wrong with spending generously on a birthday when the expense comfortably fits the family budget and genuinely matters to the child. The problem begins when parents feel they must compete with social-media parties, other families, or unrealistic expectations and stretch their finances to keep up. Bankrate reported in 2025 that 31% of U.S. adults were willing to take on debt for discretionary purchases, a useful reminder that optional spending deserves boundaries. Setting a total budget first, then letting your child choose one or two priorities, can keep kids’ birthday party costs from overshadowing the reason everyone gathered.

Have children’s birthday parties become unnecessarily expensive, or are today’s bigger celebrations worth the money—what would you cut first, and why? Share your thoughts in the comments.

What to Read Next

Your Child Got Birthday Money — Should You Let Them Spend All of It?

The $500 Birthday Party Question: When Did Kids’ Birthdays Get So Expensive?

6 Birthday Gift Hacks That Won’t Break Your 2026 Budget

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: birthday party costs, Family Budget, family finances, Kids, kids birthday parties, Parenting, party planning, Saving Money

Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Baby

9 Baby Names Inspired by Fall Without Naming Your Child Autumn

Evan Morgan
Baby

10 Vintage Baby Names That Sound Surprisingly Modern Again

Evan Morgan
Baby

9 Baby Names That Sound Expensive Even Though Naming Your Baby Is Still Free

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette