• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

Should Grandparents Be Expected to Help Pay for Kids’ Activities?

September 9, 2026 | Leave a Comment

Grandparents And Family
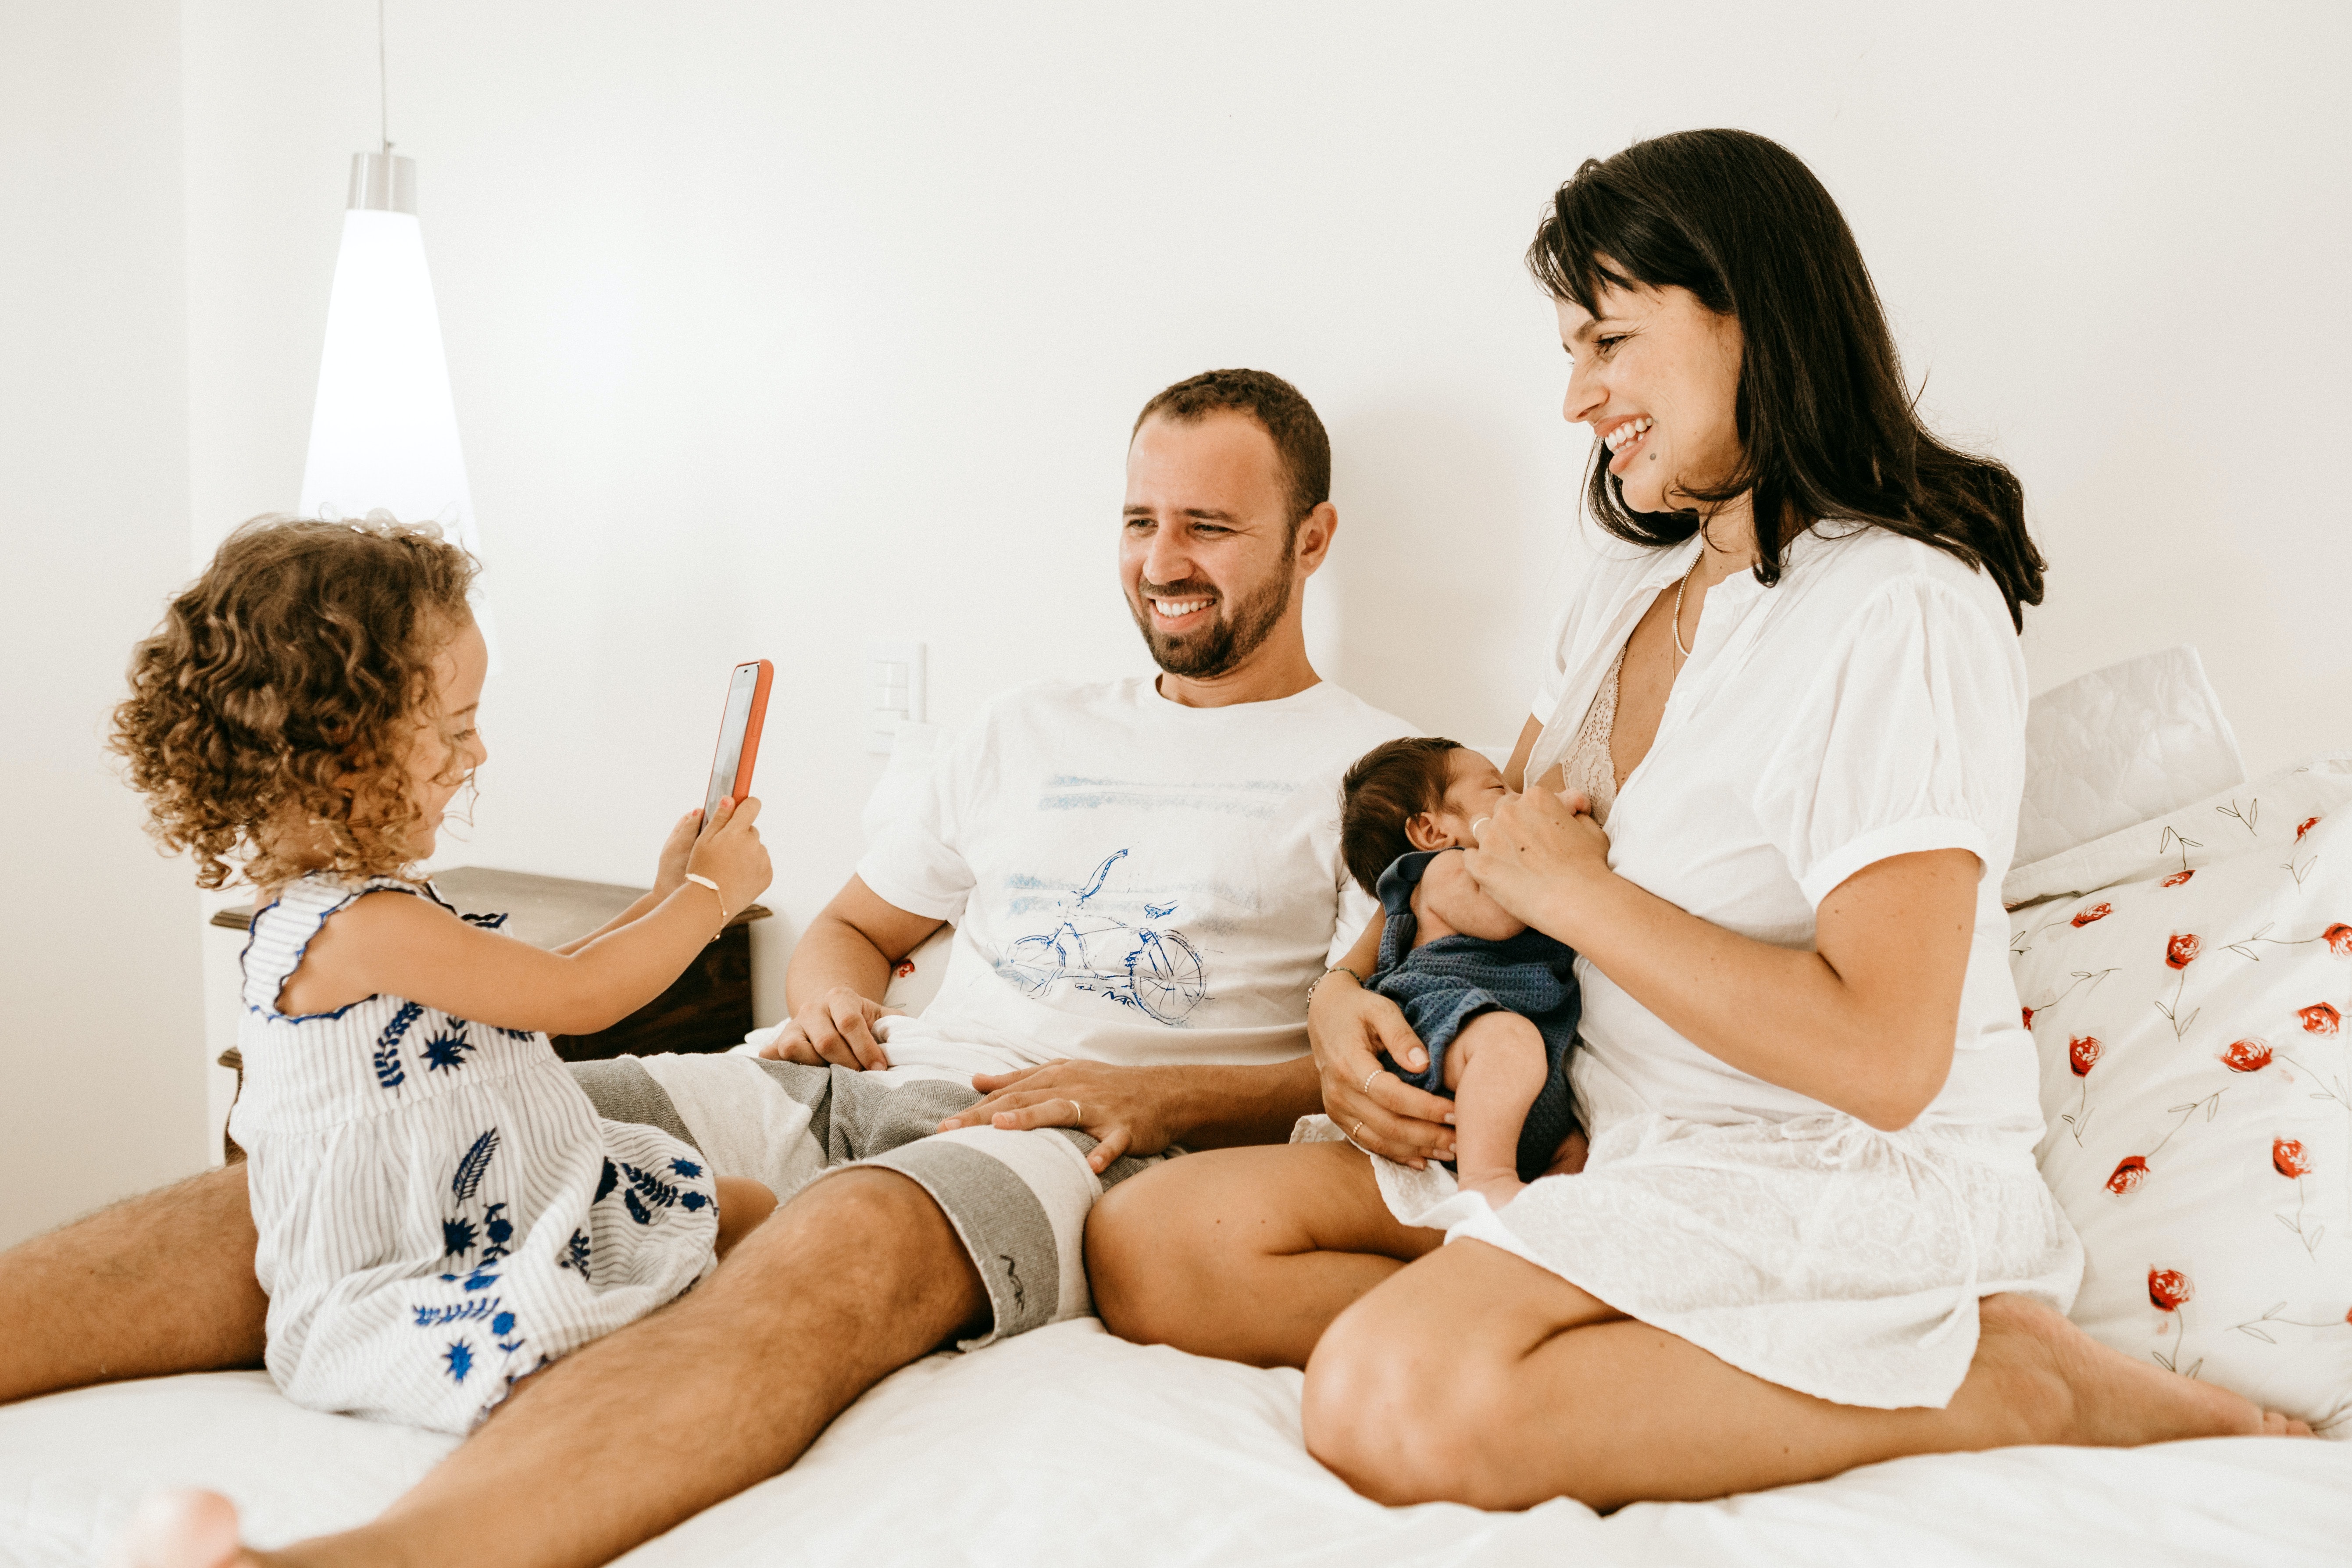
Kids’ sports, camps and lessons can cost families thousands of dollars a year, making grandparents’ financial help tempting. Clear boundaries can keep that generosity from becoming an expectation. (Pexels).

Soccer registration is $400. The uniform is another $150. Then come tournament fees, hotels, gas, team photos and the inevitable new pair of cleats halfway through the season.

For parents already juggling groceries, housing, childcare and other household expenses, asking Grandma or Grandpa to help may not sound unreasonable—especially when grandparents are financially comfortable and eager to be involved.

But when does a generous gift turn into an expectation?

That’s becoming a more consequential family-finance question as organized children’s activities get more expensive and grandparents provide enormous amounts of financial and caregiving support to younger generations. New AARP research estimates grandparents collectively provide about $172 billion in direct financial assistance to grandchildren every year, on top of hundreds of billions of dollars worth of unpaid care.

There’s nothing wrong with a grandparent wanting to pay for soccer, dance or summer camp. The financial danger begins when parents build recurring expenses around money Grandma and Grandpa never actually promised.

Kids’ Activities Are Getting More Expensive

The cost of organized activities makes it easy to understand why parents might welcome another source of financial help. The Aspen Institute’s Project Play found that the average U.S. sports family spent $1,016 on a child’s primary sport in 2024, up 46% from $693 in 2019, with families spending another $475 on average for that child’s additional sports.

Those aren’t merely inconvenient expenses: Project Play has warned that rising costs contribute to significant participation gaps between children from higher- and lower-income households. And registration may only be the beginning when a sport requires specialized equipment, private instruction, tournament travel, hotels or repeated uniform purchases. When one child’s activity begins costing four figures a year, asking whether grandparents might want to contribute becomes understandable—but affordability for the parents doesn’t automatically establish a financial obligation for the grandparents.

Grandparents May Already Be Contributing More Than Anyone Realizes

Before asking grandparents to pick up another bill, families may want to consider the financial value of help they’re already receiving. AARP’s 2026 research found that 90% of grandparents provide financial support to grandchildren, spending an average of $2,654 annually across all their grandchildren, while 69% provide childcare.

When researchers put a value on both forms of support, the numbers became enormous: an estimated $172 billion in direct financial assistance plus $731 billion worth of unpaid care each year. That works out to a roughly $903 billion “grandparent economy,” with support ranging from birthday gifts and camps to clothing, school supplies, childcare, basic necessities and healthcare. A grandparent already providing weekly childcare, school pickups, meals and occasional financial help may therefore be contributing substantially to the household even if they never write a check for soccer registration.

Helping Should Not Become An Expectation

There is a significant difference between a grandparent volunteering to pay for piano lessons and a parent sending a $900 travel-team invoice expecting reimbursement. Grandparents may have mortgages, medical expenses, insurance premiums, long-term care concerns and retirement goals that are not obvious to younger family members. Fidelity’s 2026 retirement research found that 74% of Americans surveyed had a plan for reaching their retirement goals, underscoring the importance many households place on maintaining long-term financial security. A grandparent should not have to weaken that security simply because a child wants an expensive extracurricular opportunity. Grandparents paying for activities works best as voluntary generosity rather than an unwritten family obligation.

Families Can Find A Middle Ground

Financial support does not have to be an all-or-nothing arrangement. A grandparent who cannot comfortably cover a $1,500 sports season might offer $200 toward registration, buy equipment for a birthday or pay for several music lessons instead. Another practical approach is choosing one activity each year that grandparents want to support, creating a predictable boundary for both generations. Parents can also ask whether grandparents would rather contribute time by driving children to practices, attending performances or helping with childcare, support that can be valuable without requiring another check. When discussing grandparents paying for activities, specific limits can prevent a generous gesture from quietly turning into a recurring financial commitment.

Parents And Grandparents Need An Honest Conversation

Money becomes especially uncomfortable when family members make assumptions instead of discussing expectations directly. Parents can start by explaining the activity, its total cost and why it matters to the child, then asking whether the grandparent would be interested in contributing rather than implying that help is required. Grandparents should feel equally comfortable saying, “I can contribute $300 this year,” or declining altogether without being made to feel less supportive. Fidelity’s 2025 Family and Finance Study emphasized that ongoing family conversations about money and responsibilities can create greater clarity, a principle that applies to smaller financial decisions as well as major estate planning. Clear communication around grandparents paying for activities can protect relationships while ensuring everyone understands who is responsible for future bills.

Ask One Question Before Saying Yes

A useful question for grandparents isn’t simply, “Can I afford the $800?” but “Can I afford for the family to expect this $800 again next year?” Paying one season of travel soccer from surplus cash is different from creating a recurring commitment that continues for several grandchildren over many years. Grandparents should consider whether the gift competes with retirement contributions, emergency savings, debt repayment, medical expenses, insurance premiums or money they may eventually need for long-term care. They should also think about fairness if several grandchildren participate in activities with dramatically different price tags, because paying $2,000 for one child’s travel team can create expectations elsewhere in the family. If the answer is yes only because the grandparent would need to carry a credit-card balance, withdraw retirement money unexpectedly or reduce money reserved for their own necessities, the activity probably doesn’t fit their budget.

The Best Support Respects Everyone’s Budget

Grandparents can play an extraordinary role in a child’s life without becoming a second set of parents financially. If they genuinely want to fund soccer, ballet, robotics camp or another experience and can comfortably afford it, their contribution can create memories and opportunities that last far beyond the season. But parents should generally build children’s activities around their own household budget first rather than treating grandparents’ money as guaranteed income. Grandparents paying for activities should be viewed as a gift, not a requirement, and no extracurricular program is worth creating resentment or threatening someone’s retirement security.

Would you expect grandparents to help pay for their grandchildren’s activities, or should those expenses remain entirely the parents’ responsibility? Share your thoughts and experiences in the comments.

What to Read Next

The Grandparent Spending Problem: What to Do When They Keep Buying Your Kids Everything

8 Things Grandparents Buy Kids That Parents Secretly Wish They Wouldn’t

6 Budgeting Hacks from Depression Era Grandmothers

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: extracurricular activities, Family Budgeting, family finances, grandparents, kids activities, Parenting, Retirement, youth sports

Should Parents Charge Adult Kids Rent When They Move Back Home?

August 21, 2026 | Leave a Comment

Bedroom
As more adult children live with their parents, families are deciding whether charging rent can protect household finances while helping young adults build independence. A clear plan for rent, savings, expenses, and a move-out goal can help both generations know what to expect. (Unsplash).

Moving back home as an adult is no longer unusual. In 2023, 18% of Americans ages 25 to 34 lived in a parent’s home, according to Pew Research Center, and housing costs, job changes, student debt, divorce, and saving for a home can all make returning to the family home financially attractive. For parents, however, opening the door raises an uncomfortable question: Should you charge your adult child rent or give them a financial break? There is no universal dollar amount that works for every household, but there is a useful rule: The arrangement should improve the adult child’s financial position without damaging the parents’ financial security. Done thoughtfully, rent can create structure and independence without turning Mom and Dad into landlords.

Charging Rent Can Protect the Parents’ Finances

Before deciding that living at home will be free, calculate what another adult actually adds to groceries, utilities, transportation, insurance, subscriptions, and other household expenses. That is particularly important for parents approaching retirement, when there may be fewer working years available to replenish money spent supporting an adult child. A Bankrate survey of parents with adult children found 61% had made financial sacrifices to help their children, including 43% who sacrificed emergency savings, 41% who delayed paying down debt, and 37% who sacrificed retirement savings. If an employed 28-year-old is living rent-free while a 60-year-old parent reduces retirement contributions to cover the increased household costs, the arrangement deserves another look. Parents should establish what they can genuinely afford to contribute before deciding what their adult child should pay.

Rent Should Have a Purpose, Not Just a Price

Charging $500 because “$500 sounds fair” misses an important opportunity to decide what the living arrangement is supposed to accomplish. Is the adult child trying to eliminate $15,000 in credit-card debt, accumulate a $20,000 apartment or home fund, recover financially after divorce, or simply find cheaper housing indefinitely? A 26-year-old earning $3,500 a month might, for example, pay $500 toward household costs while automatically saving another $700 toward moving out. Pew found that financial contributions are already normal among young adults living with parents: 72% contribute financially in some way, including 65% who help with household expenses and 46% who contribute toward rent or the mortgage. A good rent arrangement should therefore answer two questions at once: What is fair to the parents, and how is this helping the adult child become more financially independent?

Sometimes Charging No Rent Is the Smarter Choice

There are circumstances when charging rent can actually slow the goal everyone is trying to achieve. Suppose your daughter can afford $800 a month, but she has $8,000 of high-interest credit-card debt and agrees to put that entire $800 toward the balance while living at home. Giving her a temporary rent-free window could potentially get her out of expensive debt faster than collecting household rent and leaving the card balance lingering. Pew found that 64% of young adults living with parents said doing so had a positive impact on their personal finances, suggesting that moving home can genuinely function as a financial reset. The key word is temporary: “Stay here free until you get back on your feet” is vague, while “Stay rent-free for six months while paying $800 monthly toward your credit card” creates a measurable plan.

Use a Simple Test to Decide What the Rent Should Be

Instead of automatically using the local market rent for a bedroom, start with the parents’ actual financial situation. Calculate the additional household costs created by another adult, determine whether the parents need a contribution to avoid subsidizing those expenses, and then consider the child’s income and financial objective. For example, parents spending an additional $350 a month because their son moved home might charge $400 or $500 rather than the $1,200 he would pay for an apartment, leaving him significant room to save while preventing his parents from absorbing the expense. Alternatively, financially secure parents might charge more and secretly save some of the rent to return later, although that strategy should not replace teaching the child to save independently. The right amount is not necessarily the highest amount the parents could charge; it is an amount that protects both generations while supporting the purpose of the move.

Don’t Let Helping Your Child Delay Your Own Retirement

This deserves more emphasis than the original draft gives it because parents can recover from many financial decisions more easily than they can recover lost retirement years. A 30-year-old moving home potentially has decades of earnings ahead, while parents in their late 50s or 60s may be approaching the end of their highest-earning years. Fidelity’s 2026 guidance for parents with adult children living at home specifically recommends understanding your own income, expenses, and retirement needs before deciding how much support you can provide. Parents should be especially cautious if supporting an adult child requires withdrawing from retirement accounts, stopping retirement contributions, carrying credit-card balances, draining emergency savings, or postponing debts they need to eliminate before retiring. Generosity makes considerably less financial sense when Mom and Dad may eventually need financial assistance from the same children they are supporting today.

What If Your Adult Child Can Afford Rent but Doesn’t Want to Pay It?

An employed adult living at home indefinitely presents a different situation from someone recovering from a layoff or trying to escape high-interest debt. If your child has enough disposable income for frequent travel, restaurant meals, expensive electronics, or a new vehicle but says contributing to household expenses is unaffordable, the disagreement may be about priorities rather than income. Parents do not have to subsidize discretionary spending simply because their child would rather use earnings elsewhere. A reasonable household contribution can help recreate one financial reality of independent adulthood: housing and utilities have to be paid before entertainment and lifestyle upgrades. That does not require charging market rent, but it does require both generations to agree that living at home is financial assistance rather than an unlimited entitlement.

Put the Agreement in Writing Before the Moving Boxes Arrive

Money is only one source of friction when an adult child returns home, so establish the entire arrangement beforehand. Fidelity recommends setting clear financial and nonfinancial expectations, including household contributions, chores, meals, savings goals, and how long the arrangement is expected to last. A simple agreement could say the child pays $500 on the first of every month, saves at least $750 monthly, buys groceries twice a month, handles certain chores, and sits down with the parents after six months to review progress. Privacy deserves similar clarity because an adult returning home should not automatically become the 16-year-old who once occupied the same bedroom. Discuss guests, overnight visitors, shared spaces, food, parking, chores, quiet hours, pets, and other predictable sources of conflict before everyone is irritated by them.

Add an Exit Goal, Not Just an Exit Date

“You’re moving out in one year” sounds clear, but financial milestones can make the arrangement more productive. A child might agree to move when she has eliminated $10,000 of debt and accumulated a $6,000 emergency fund, or when she has saved enough for a security deposit, moving expenses, and three months of basic expenses. Parents and adult children can then review progress every few months rather than waiting until month 11 to discover that little has changed. If circumstances change because of unemployment, illness, or another legitimate setback, the plan can change too. The goal is not to rush someone out of the house; it is to prevent temporary assistance from drifting into permanent dependence without anyone consciously choosing it.

Consider the “Rent Now, Gift Later” Strategy Carefully

Some parents choose to charge rent and quietly save the money, intending to return it when their child buys a home or moves out. Fidelity describes exactly this type of strategy in its discussion of adult children returning home, although the family featured ultimately chose another approach. It can create a useful forced-savings windfall, but there is also an argument for telling the adult child to build those savings personally so they learn to manage the money themselves. Parents who intend to return a significant amount should also consider whether there could be tax or estate-planning implications based on the amount and circumstances. Either approach can work, but it should fit the larger objective rather than becoming another financial secret between parents and their adult child.

The Best Arrangement Should Leave Both Generations Better Off

There is no universal answer to whether parents should charge adult kids rent because a struggling 22-year-old graduate, a 29-year-old saving for a first home, and an employed 38-year-old moving home indefinitely present very different situations. What matters is whether the arrangement protects the parents’ emergency savings and retirement while helping the child make measurable progress toward financial independence. Before anyone moves in, answer five questions: How much will the child contribute, what will they save or pay down, what household responsibilities will they assume, how long is the arrangement expected to last, and what does successful moving out look like? If nobody can answer those questions, deciding whether rent should be $0, $400, or $800 is probably premature.

If your adult child moved home tomorrow, would you charge rent, offer free housing with conditions, or create another arrangement—and why?

What to Read Next

43% of Parents Would Go Into Debt to Help Their Kids Fit In — 7 Money Traps to Avoid

Youth Sports Cost Families $1,016 a Year on Average — 8 Expenses New Parents Don’t Expect

Should Kids Get Paid for Good Grades? What Parents Should Consider Before Offering Cash

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: adult children, family finances, financial independence, living at home, money management, multigenerational households, Parenting, personal finance, rent, Retirement

15 Surprising Changes If 70 Becomes The New Retirement Age In The US

June 3, 2024 | Leave a Comment

Canva

As the conversation around retirement age intensifies in the United States, the prospect of pushing the retirement age to 70 is gaining traction. This shift would bring about significant and surprising changes across various aspects of life. Here’s a closer look at what could happen if 70 becomes the new retirement age.

1. Extended Workforce Participation

Canva

If 70 becomes the standard retirement age, millions of Americans will remain in the workforce longer. This change means people will need to adapt to longer careers, potentially leading to increased opportunities for career advancement. Additionally, businesses might benefit from the experience and knowledge of older employees. However, it could also mean fewer job openings for younger workers, impacting the job market dynamics.

2. Increased Healthcare Demand

Canva

As older individuals continue to work, the demand for healthcare services is likely to rise. Employers may need to offer more comprehensive healthcare plans to cater to the needs of aging employees. This shift could also spur growth in industries focused on elder care and wellness programs. Moreover, the increased stress and physical demands of prolonged work could lead to higher healthcare costs for both individuals and businesses.

3. Social Security System Revisions

Canva

Raising the retirement age to 70 would necessitate changes to the Social Security system. Benefits could be delayed, which might help extend the solvency of the Social Security Trust Fund. On the flip side, individuals who rely on these benefits may face financial challenges if they are unable to work until 70 due to health issues or job market conditions.

4. Financial Planning Adjustments

Canva

With a later retirement age, financial planning strategies will need to evolve. Americans will have to rethink their savings goals, investment timelines, and retirement plans. Financial advisors might recommend more aggressive savings plans and diversified investment portfolios to ensure sufficient funds for a longer retirement period. Additionally, the emphasis on long-term financial health will become more pronounced.

5. Changing Dynamics in the Workplace

Canva

A significant presence of older employees will alter workplace dynamics. Companies may need to invest in training programs tailored to different age groups to ensure that older workers can keep up with technological advancements. Intergenerational collaboration could foster innovation, but it might also require new policies to manage age diversity and prevent ageism.

6. Impact on Pensions and Retirement Funds

Canva

Pension plans and retirement funds will be affected by the shift in retirement age. Employers might revise their contributions and benefits structures to accommodate longer working periods. Employees will need to stay informed about changes to their pension plans and may need to adjust their retirement savings strategies accordingly.

7. Shift in Consumer Behavior

Canva

Older workers tend to have different spending habits compared to their younger counterparts. With more people working into their 70s, there could be a shift in consumer behavior, with increased demand for products and services catering to an older demographic. This trend could create new market opportunities for businesses focusing on health, leisure, and technology designed for senior citizens.

8. Enhanced Lifelong Learning

Canva

The necessity to stay competitive in the job market will drive lifelong learning initiatives. Older employees will seek continuous education and skills development to maintain their employability. Educational institutions and online learning platforms might see a rise in enrollment from older adults looking to upskill or change careers later in life.

9. Changes in Family Dynamics

Canva

Family dynamics could also shift with a later retirement age. Grandparents may have less time to spend with grandchildren, potentially affecting family relationships. Additionally, the financial burden on younger family members might increase as they may need to support their aging parents longer if those parents are unable to work up to the new retirement age.

10. Psychological and Emotional Impact

Canva

Working longer can have significant psychological and emotional impacts. While some may find continued employment fulfilling, others might experience increased stress, burnout, or dissatisfaction. Mental health support will become crucial in helping older workers manage the challenges associated with extended careers.

11. Policy and Legal Adjustments

Canva

Federal and state policies will need to adapt to the new retirement age. Labor laws, retirement benefits, and age discrimination policies might undergo significant revisions to protect the rights and well-being of older workers. This regulatory evolution will be crucial in ensuring fair treatment and opportunities for all age groups in the workforce.

12. Technological Adaptation and Inclusion

Canva

As technology continues to advance, older workers will need to adapt to new tools and platforms. Companies will have to prioritize technological inclusion, offering training and support to ensure that all employees, regardless of age, can utilize the latest technologies effectively. This inclusion will be key to maintaining productivity and competitiveness.

13. Economic Implications

Canva

Raising the retirement age could have broad economic implications. On one hand, it may boost the economy by increasing the labor force participation rate and reducing the burden on Social Security. On the other hand, it could strain public services and healthcare systems as the aging population remains active in the workforce longer.

14. Impact on Retirement Lifestyle

Canva

The concept of retirement will undergo a transformation. Instead of viewing retirement as a period of complete leisure, individuals might adopt a more gradual transition into retirement, balancing part-time work and personal pursuits. This shift will redefine what it means to be retired and could lead to more diverse and fulfilling post-career lifestyles.

15. Evolution of Retirement Communities

Canva

Retirement communities and housing will need to evolve to meet the needs of an older, more active population. These communities might offer more amenities and opportunities for continued learning and engagement. The focus will shift towards creating environments that support both independent living and professional engagement for those who choose to work longer.

Preparing for a New Era of Retirement

Canva

As the possibility of raising the retirement age to 70 looms, it’s essential for individuals, businesses, and policymakers to prepare for the profound changes it will bring. From healthcare and financial planning to workplace dynamics and family life, every facet of society will feel the impact. Embracing these changes proactively can help ensure a smoother transition and a more sustainable future for all.

Ashleigh Clyde
Ashleigh Clyde

Ashleigh Clyde is a dedicated youth advocate, journalist, and researcher. Passionate about shedding light on important issues, such as financial literacy and marketing tactics. She has extensive experience in entertainment journalism.

Filed Under: Money and Finances Tagged With: new retirement age, Retirement, retirement age, Social Security

How New Parents Can Tap Their Retirement Savings Penalty Free

April 9, 2020 | Leave a Comment

Becoming a parent or adding a baby, while an exciting time, can also be stressful.  Of course, there are the sleepless nights and the round the clock baby care, but there are also financial considerations.  Many people are surprised how many expenses come with the birth of a baby.  And, you must also consider who will care for the child.  In the United States, maternity and paternity leave are not universal.  If you or your partner want to stay home for a few weeks after the baby is born (or adopted) and you don’t have maternity/paternity leave, you’ll either need to save money for it or find a way to cover your expenses while you stay home.  If you fall into the latter category, it’s important to learn how new parents can tap their retirement savings penalty free.

How New Parents Can Tap Their Retirement Savings Penalty Free

Thank the SECURE Act

The SECURE Act (short for The Setting Every Community Up for Retirement Enhancement Act), which passed in December 2019, now allows parents who’ve had a baby or adopted a child within the past year to take up to $5,000 out of their retirement account penalty free.  If each parent has their own retirement account, each individual can take out $5,000, meaning the couple can take out $10,000 total.

Normally, if a person takes money out of their retirement account before 59.5 years of age, they have to pay a 10% penalty.  The SECURE Act eliminates this penalty for new parents.

How New Parents Can Tap Their Retirement Savings Penalty Free
Photo by Jonathan Borba on Unsplash

Taxes Still Need to Be Paid

While you won’t have to pay the penalty, you will still have to pay taxes on the withdrawal.  Whether you withdraw $5,000 or $10,000 (if both partners withdraw $5,000), that money will appear as income on your tax form, and you will have to pay taxes on it.

Why You Should Carefully Consider Using this Option

While knowing how new parents can tap their retirement savings penalty free when you’ve had a baby is a nice option, you should try to avoid tapping your retirement for a number of reasons.

You Lose Compounding Interest

If you take $5,000 out of your retirement income, you lose the compounding interest that money was making for you.  Every month, that money was generating income, and now, it won’t be.

May Start a Dangerous Precedence

Retirement funds are for retirement.  Once you start pulling from your retirement, you may start doing that regularly.  It’s very easy to start thinking of your retirement account as a de facto emergency fund and pull money from it whenever you have an unexpected expense.  If you get into this pattern, you can easily decimate your retirement account.

I have a friend whose child had emotional issues, so my friend was desperate to help her child.  She sent him to residential treatment facilities and wilderness camps to try to help her son get his behavior under control.  Her insurance wouldn’t pay for these treatments, so she relied heavily on pulling money from her retirement account.  Now, her son is grown and still having emotional problems.  She, meanwhile, has emptied her retirement account and is starting over, trying to build a new retirement fund at the age of 45.  It’s not a good place to be.

Payback Options

Of course, you can take out the money, pay your taxes, and be done with it.  However, if you want to make up for what you had to take out, there are ways to do so.

Pay It Back Within Two Months

Check with your financial advisor, but for many retirement accounts, if you withdraw money from your retirement account and can return that money back to the account within two months, it’s as if you never withdrew the money.  You won’t have to pay taxes on it.  Think of it as a short-term, two-month loan.

This can be an excellent way to get a short-term loan, IF you can pay it back quickly.  This may help you if you want to take a one-month, unpaid paternity leave and know you can get the money back into your retirement fund the next month.

Pay It Back Overtime

Another option is to gradually pay it back over time.  Under this option, you still have to pay taxes on your distribution.  However, by paying back the money to your retirement account, you gain back the power of compounding interest on the money you originally withdrew.  With this strategy, your retirement account will be healthier and more robust than if you simply withdrew the money and never paid it back.

Other Times You Can Withdraw from Your Retirement Account Penalty Free

Beyond how new parents can tap their retirement savings penalty-free within a year of having a new baby or adopting a child, there are other times people can tap their retirement accounts penalty free.  However, before considering taking money out for any other reason besides having or adopting a child, consult your financial advisor.  Some rules differ depending on the type of retirement account you have (IRA or 401K).

Educational Expenses

You can tap your retirement account penalty free for related higher education expenses such as tuition, fees, supplies and books.  This money can be used for your own higher education, or for your spouse or children.

How New Parents Can Tap Their Retirement Savings Penalty Free
Photo by MD Duran on Unsplash

First-Time Home Purchase

If you’re a first-time home buyer, you can take $10,000 out penalty free to use as the down payment on your new home.  If your spouse has his or her own retirement account, he or she can also withdraw $10,000, giving you up to $20,000 toward your new home.

Medical Expenses

Some years you may incur significant medical expenses in a year (i.e. greater than 10% of your annual income).  During those years, you can take money out of your IRA to pay for medical bills without incurring a penalty.

Final Thoughts

The SECURE Act gives new parents flexibility when it comes to their retirement withdrawals.  However, keep in mind, whether you withdraw money for a new child or for any of the other reasons you can withdraw money penalty-free, you still will have to pay taxes.  You’ll also be losing the power of compounding interest on that money, which may be the biggest hit of all.

Melissa Batai
Melissa Batai

Melissa is a writer and virtual assistant. She earned her Master’s from Southern Illinois University, and her Bachelor’s in English from the University of Michigan. When she’s not working, you can find her homeschooling her kids, reading a good book, or cooking. She resides in Arizona where she dislikes the summer heat but loves the natural beauty of the area.

Filed Under: Money and Finances Tagged With: 401k, financially afford children, having children, IRA, Retirement

What Fate for Annuities?

September 3, 2012 | Leave a Comment

Use a calculator to determine your annuties rates
Image: FreeDigitalPhotos.net

As the Eurozone crisis rages, many people approaching retirement age will be worried about how they fit in to the wider picture of financial security – especially in relation to annuities, which have been falling more or less constantly in recent years.

An annuity is a regular income paid out in exchange for a lump sum, usually after years of paying into a tax-free pension fund. They’re intended to be guaranteed for life, irrespective of lifespan (although the amount in each regular payout is age-dependent).

What is the Fate of Annuities?

For the lucky few who retired when the market peaked, it’s all cruises and second homes. But for those currently awaiting an annuity, the outlook doesn’t look as rosy.

Pensioners have in fact been getting squeezed for longer than most, with many reports citing a year on year drop off in rates since the early nineties. So what is happening to annuity rates? And how can people prepare for them to continue falling?

In short, the ongoing financial meltdown in Greece has severely dented the confidence of many investors, who have moved their money to British and German bonds, resulting in rising prices and falling yields.

What About Other Investments?

Of course it goes much deeper than that. Increased life expectancy has lowered the returns for everyone approaching retirement, as has a move towards more gender equality between annuity prices. In the face of an aging population, many governments and banks are in denial about the prospects for pensioners, arguing that the rising value of bonds will compensate for lower rates.

But many people simply don’t invest in bonds or corporate funds, and are wholly reliant on stable annuity rates. Those feeling the pinch are advised to seek some alternatives for their future financial security, and to shift their focus away from traditional annuities.

Remember, once you buy an annuity the rate is fixed, so even if rates go up in the future, your payments remain the same. Cast around on the web by searching for best annuity rates UK, and look at alternative investment funds (this article offers some solid advice on investment) so you can stop worrying and start enjoying your retirement.

 How have lower rates on annuities affected your retirement accounts?

Sponsored Article

Brian
Brian

Brian is the founder of Kids Ain’t Cheap and is now sharing his journey through parenthood.

 
Email • Google + • Facebook • Twitter

Filed Under: Money and Finances Tagged With: Annuities, money, Retirement

  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Baby

9 Baby Names Inspired by Fall Without Naming Your Child Autumn

Evan Morgan
Baby

10 Vintage Baby Names That Sound Surprisingly Modern Again

Evan Morgan
Baby names

Teachers Admit: These 6 Baby Names Create Instant Bias in the Classroom

Latrice Perez

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette